How to Use G-Force Funding’s SBA Loan Calculator

G-Force Funding launched its free SBA loan calculator to help small-business owners explore potential loan payments. Use the tool to compare loan amounts, interest rates and repayment terms before discussing financing with a lender.
How to use the SBA loan calculator
- Enter a loan amount. Start with the amount you expect to borrow for your business project.
- Enter an interest rate. Use a lender’s quoted rate or a clearly labeled planning assumption.
- Choose a repayment term. Use the term offered for the financing you are considering.
- Compare the estimates. Review the monthly payment and total interest, then change one input at a time to see how the result changes.
Use the results to prepare questions for a lender
A payment estimate can help you assess how a proposed loan might fit your business’s monthly budget. Ask the lender for a complete repayment schedule and a breakdown of fees, closing costs and any other charges. Confirm whether the interest rate is fixed or variable and how a rate change would affect your payments.
The calculator is a planning tool. Its results are estimates, not a loan offer, eligibility decision or guarantee of approval. Actual payments and borrowing costs depend on the loan agreement; costs not included in the calculator inputs may change the total.
Learn about SBA financing
The SBA’s official 7(a) loan overview explains program uses and eligibility. A participating lender determines whether your business qualifies and what terms are available.
Discuss your business funding needs
G-Force Funding is based in Miami and helps small businesses explore financing options. Contact G-Force Funding with your funding goal, estimated amount and timeline, or call (305) 563-4361.
Try the SBA loan calculator and bring your estimates to the conversation.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
10 Financial Planning Checks for Small Business Growth
Updated September 30, 2026.
Small-business growth needs more than higher sales. A useful financial plan connects margins, cash flow, operating capacity and funding obligations. These ten checks help evaluate expansion before committing money.
1. Define a measurable growth project
Specify the product, location, capacity or customer group you want to expand. Set a budget, timeline and success measure. Separate essential costs from optional spending.
2. Forecast cash, not just profit
Map when customers pay and when suppliers, staff and lenders must be paid. A profitable sale can still create a cash gap. Review the forecast regularly against actual results.
3. Check unit economics
Calculate the contribution remaining after the direct cost of a sale. Include discounts, returns, shipping and service time where relevant. More revenue does not necessarily mean more profit.
4. Improve collections and supplier planning
Invoice promptly, resolve disputes and follow up on overdue accounts. Negotiate payment terms openly instead of letting obligations become delinquent. Compare early-payment discounts with their cost to your margin.
5. Evaluate equipment and technology
Estimate installation, training, maintenance and downtime alongside the purchase price. Use our equipment cost checklist before financing a purchase.
6. Measure customer acquisition and retention
Track the cost of acquiring a customer, repeat purchases and the margin those sales produce. Test marketing changes on a manageable scale before committing a large budget.
7. Keep financial records current
Reconcile accounts and review receivables, payables and debt. Our bookkeeping guide outlines a practical routine.
8. Match financing to the project
Compare funding structures using net proceeds, payment timing, total cost, collateral and guarantees. A favorable-sounding rate or quick application does not establish that borrowing fits the business.
9. Test downside scenarios
Model slower sales, delayed opening, higher costs or late customer payments. Identify which spending can be delayed and what reserves you need. Avoid depending on refinancing that is not committed.
10. Set review points
Choose dates to compare results with the plan. Decide in advance which measures would prompt you to continue, adjust or stop the project. Record lessons so the next investment decision uses better evidence.
Prepare a financing discussion
Bring your project budget, recent financial records, existing obligations and forecast. Our application checklist can help.
Contact G-Force Funding or call (305) 563-4361 to discuss financing needs. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Bridge Loans: Costs, Risks and Repayment Planning
Updated September 30, 2026.
A business bridge loan is short-term financing intended to cover a gap before a planned repayment source becomes available. That source might be a sale, customer receipts or longer-term financing. The central question is whether the business can repay if the expected event is delayed or does not happen.
Start with a specific funding gap
Identify the expense, amount and deadline. A temporary collection delay is different from a continuing operating loss. Bridge financing cannot make an unprofitable project viable simply by postponing payment.
Document the exit plan
- Customer receipts: When are payments due, and what evidence supports collection?
- Asset sale: Is a buyer committed, and what conditions remain?
- Refinancing: Is there a written commitment or only an expectation?
- Investor funding: Are funds committed and available on the required timetable?
Ask what happens if the loan matures before that event. Extensions and refinancing are not guaranteed, and additional fees or default consequences may apply.
Test a delayed repayment scenario
Illustrative scenario: A business expects a customer payment in 60 days but considers financing due in 90 days. Model collection at 120 days as well. Determine how scheduled payments and the maturity balance would be covered during the delay. A positive forecast is not enough without a workable backup.
Compare the full cost and obligations
Request net proceeds, interest, fees, payment frequency, maturity, any balloon payment and early-repayment terms. Review collateral, guarantees, default provisions and the cost and conditions of an extension. Fast funding claims remain subject to underwriting and closing requirements.
Consider other structures
A business line of credit may address recurring gaps if the facility fits your business. Eligible receivables may support financing or invoice factoring, with different costs and obligations. A planned long-term expense may be better evaluated as a term-loan project.
These are alternatives to investigate, not interchangeable “bridge loans.” A merchant cash advance, for example, can have a different legal and pricing structure.
Prepare before applying
Gather business financial records, a debt schedule, evidence supporting the repayment event and a cash-flow forecast that includes delays. If property is pledged, also review real-estate collateral risks.
Discuss your financing needs with G-Force Funding or call (305) 563-4361. Availability, approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
6 Startup Business Funding Options: Loans, Grants and More
Startup business funding can come from loans, personal resources or sources that do not require borrowing. Compare each option against your startup budget, expected cash flow and the obligations you are prepared to accept.
Updated September 30, 2026. This guide combines our overlapping articles about six startup funding options.
1. SBA microloans and community lenders
The SBA microloan program provides loans of up to $50,000 through nonprofit intermediary lenders. Eligible uses include working capital, inventory and equipment. Microloan proceeds cannot be used to pay existing debts or purchase real estate. The intermediary makes credit decisions and sets the terms.
Ask about eligibility, required documents and available business counseling before applying. Approval is not automatic, and requirements vary by lender.
2. Funding from friends and family
First agree whether the money is a gift, a loan or an ownership investment. For a loan, put the amount, payment schedule and expectations in writing. For an investment, clarify ownership and decision-making rights. Everyone involved should understand that the business could fail and the money could be lost.
3. Business credit cards
A credit card may help pay for smaller business purchases, but a balance carried over time can become expensive. Compare the interest rate, fees and any promotional period. Check whether a personal guarantee is required and plan how you would repay the balance if sales are delayed.
4. Personal loans permitted for business use
Some entrepreneurs consider personal loans when business financing is unavailable. Confirm that the lender allows business use of the proceeds. The borrower remains personally responsible for repayment even if the business does not succeed. Compare the full payment schedule and total borrowing cost before committing.
5. Crowdfunding
Rewards-based crowdfunding can help test demand for a product, but a campaign needs a realistic marketing and fulfillment budget. Calculate platform fees, production costs and shipping before promising rewards. Equity crowdfunding involves selling an ownership interest and has different legal requirements; review the platform’s rules and obtain qualified advice before offering an investment.
6. Targeted grants
Look for programs that specifically match your business, location, industry or project. Read the eligibility rules, permitted uses, deadlines and reporting requirements. Treat an application as uncertain funding until an award is confirmed. A grant is different from a loan and should not be presented as guaranteed startup capital.
How to compare your options
- Amount and timing: Identify essential startup costs and when each bill is due.
- Repayment: Request a schedule showing payments, interest and fees for any loan.
- Personal exposure: Identify guarantees, collateral and obligations that remain if the business closes.
- Ownership: Decide whether you are comfortable sharing ownership or control.
- Eligibility: Check current revenue, operating-history and credit requirements directly with the provider.
Prepare before applying
Build a startup budget, a business plan and cash-flow projections with clearly stated assumptions. Gather any financial records the provider requests. Do not assume a quoted credit score or advertised loan amount guarantees approval.
The SBA’s business planning resources can help you organize startup costs and compare funding approaches.
Frequently asked questions
Can a startup qualify without revenue?
Some funding sources consider early-stage businesses, while others require operating history and revenue. Ask the provider before applying. Funding availability depends on your circumstances and the program’s requirements.
Are grants and crowdfunding business loans?
Not necessarily. Grants, rewards-based crowdfunding and ownership investments have different obligations from loans. Compare the actual agreement rather than treating every source of capital as debt.
What should I do about a guaranteed-approval offer?
Check the provider’s identity and written terms carefully. Do not rely on advertising as proof that you qualify or that the funding is affordable.
Discuss your funding needs
Contact G-Force Funding or call (305) 563-4361 to discuss your business stage, funding amount and timeline. Available financing depends on eligibility and lender review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Startup Funding Sources: Debt, Equity and Other Options
Updated September 30, 2026.
Startup funding can come from borrowing, selling an ownership stake, using personal resources or earning support through grants and customer campaigns. These sources create different obligations. Start by deciding how much you need, when you need it and what you can responsibly offer in return.
Debt: repayment without selling ownership
Loans and credit products require repayment under their agreements. They can preserve ownership, but interest, fees, collateral and guarantees affect the risk. A startup needs a credible repayment plan even before revenue is predictable.
Compare our six startup funding options for a product overview and our startup rate comparison checklist for evaluating offers. Credit-card promotions should be checked directly with the issuer; rewards do not replace an affordable repayment plan.
Equity: sharing ownership with investors
Angel investors and venture-capital firms may invest for an ownership interest. Equity can reduce dependence on scheduled loan payments, but it dilutes existing ownership and may give investors governance or approval rights. Fundraising takes preparation and is not assured simply because a business operates in a growing industry.
Before approaching investors, prepare a business model, financial forecast, funding purpose and explanation of the proposed ownership structure. Discuss valuation, control, future funding and exit expectations with qualified advisers. The SEC’s small-business funding roadmap explains capital-raising paths and ownership considerations.
Self-funding: setting a personal limit
Using savings preserves control but puts those funds at risk. Decide how much you can contribute while maintaining essential household expenses and reserves. Record owner contributions and keep business transactions organized. Retirement accounts and home equity involve additional risks and rules that warrant individual professional advice.
Friends and family: define the arrangement
Clarify whether funds are a gift, loan or investment. Put repayment or ownership terms in writing, explain that the business may fail and give contributors time to make an informed decision. Do not rely on an informal understanding where expectations differ.
Crowdfunding: understand what backers receive
Donation, rewards, lending and investment crowdfunding are different structures. A rewards campaign may require production and delivery; lending creates repayment obligations; investment crowdfunding involves securities rules. Review platform fees, funding conditions, refund responsibilities and applicable requirements before launching.
Build the campaign budget around fulfillment as well as fundraising. Raising $20,000 does not leave $20,000 for operations if fees, production and shipping consume part of the proceeds.
Grants: verify fit before spending application time
Grants are usually tied to specific eligibility criteria, activities or outcomes. The SBA states that it does not provide grants for starting and expanding a business. Other programs may support defined purposes, but funding is competitive and conditions matter.
Check the sponsor’s official current notice for application dates, permitted expenses, matching funds and reporting requirements. Do not build a launch budget around an unawarded grant.
Choose a mix your business can manage
- Timing: Will the money be available before a binding expense?
- Repayment: Can cash flow support debt if sales arrive late?
- Control: What ownership or decision rights are you willing to share?
- Exposure: Which business or personal resources could be lost?
- Execution: Can you meet investor, grant or customer obligations?
Use our startup loan readiness checklist if borrowing is part of your plan. Discuss financing needs with G-Force Funding or call (305) 563-4361. Funding availability and terms depend on the source and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Inventory Financing, Loans and Lines of Credit
Many retail and wholesale businesses rely on inventory to serve their customers. It’s what keeps your business afloat and keeps your customers satisfied. Even strong, lucrative businesses, however, may require additional money from time to time. Inventory financing may be able to help you receive the money you need if your business could use some extra cash and you have unsold inventory in your warehouse or storage.
What Is Inventory Financing?
Inventory financing is a type of asset-based loan where the value of some or all of your inventory is used to secure the loan. The lender gives you a loan based on a proportion of the value of your inventory, and the inventory serves as collateral for the loan. Inventory finance is commonly used by business owners to purchase new inventory, but it can also be utilized for a variety of other needs. Inventory finance can help businesses with short-term cash flow gaps or stock up on inventory in anticipation for a busy season.
Businesses that constantly have substantial amounts of inventory, such as shops, restaurants, and wholesalers, are the most common users of inventory financing. Automotive dealers, for example, must purchase significant volumes of very expensive inventory, and this inventory consumes a large portion of their capital. Even a profitable auto dealer may have limited funds to grow their operations or hire additional salespeople. Inventory financing may be able to assist in the provision of that additional capital.
Accounts Receivable Financing vs. Inventory Financing
Inventory financing uses eligible goods as collateral; accounts receivable financing relies on eligible customer invoices. Both involve valuation and collection risks. Slow-moving or obsolete inventory may lose value, while invoices may become overdue, disputed or uncollectible. A provider does not necessarily advance the full face value of an invoice or the full value of inventory. Invoice factoring also differs from a loan because it involves selling receivables.
Collateral is one part of underwriting. Approval still depends on the lender’s requirements and your business finances.

Inventory Financing Options
An inventory loan and an inventory line of credit are the two most common types of inventory financing. While both types of inventory financing use your inventory as collateral, these two loan types have significant implications for your business’s future funding.
Inventory Loan
A business loan based on the value of your inventory is known as an inventory financing loan. An inventory loan, like a conventional small business loan, is for a defined amount that is repaid in monthly payments over a set repayment term or in one lump sum after the inventory is sold. You will be responsible for repaying the entire loan amount, and if you require additional funds, you will need to take out another loan.
Inventory Line of Credit
While a loan’s funds can only be utilized once, an inventory line of credit can supply you with additional funds on a continuous, as-needed basis. Many business owners choose to get a business line of credit so that they can address any unexpected expenses that may arise. You can enter into an inventory finance agreement with a lender to set terms and conditions for a long-term business funding relationship.
Inventory Financing’s Advantages and Disadvantages
Inventory financing can connect borrowing capacity with eligible inventory, but lenders may also review credit history, cash flow and existing debts. Ask how inventory is valued, which goods are excluded, how often reports are required and whether additional collateral or a personal guarantee is needed.
Inventory financing, on the other hand, can be more expensive in the long term than paying cash for inventory, even if the interest rate is modest. Although inventory financing can be secured by the inventory itself, in some cases the lender may require extra security. A lender may like to visit your facility to ensure that the inventory being financed is being properly cared for and will not be damaged or decline in value before being sold. On-site visits are usually accompanied by an appraisal cost, which you will be responsible for paying.
Keep in mind that most lenders will only lend money for a fraction of the value of your inventory, not the entire appraised value. As a result, if you’re using inventory finance to buy inventory, keep in mind that you’ll need to put up some cash.
Obtaining Inventory Financing
Inventory financing can be obtained via a regular bank, a credit union, or an online lender. Because inventory financing can involve ongoing reporting and monitoring, it’s critical to do your research and choose the finest financing business for your company.
Inventory financing is based on the inventory’s liquidation value and the likelihood of a quick sale. Lenders will want to see documentation that shows you have a high inventory turnover and can really sell the product throughout the application process, such as:
- Balance sheet and separate sales-history reports
- P&L statements
- Estimated sales
- Statement of Cash Flow
- Business plan
Lenders will also want to verify that you have a good inventory management system in place so that they aren’t concerned that you are buying more inventory than you need and can sell.
Additional Financing Options
Inventory finance may not be ideal for your business if you don’t have a lot of inventory. There are several other methods of finance that may provide a more flexible funding choice in that instance, such as:
Working capital loan: Compare short-term business financing for eligible operating expenses. Security requirements and permitted uses depend on the agreement; these loans are not always unsecured.
Check out our in depth guide to term loans here: https://gforcefunding.com/business-term-loans-in-2021-what-are-the-best-options/
Equipment Loan: If an unsecured loan isn’t the greatest option, an equipment loan might let you buy new equipment while paying it off over time. Even if you don’t have a perfect credit history, you might be able to qualify for a secured loan.
Take a look at our guide to equipment financing here: https://gforcefunding.com/equipment-financing-what-you-need-to-know-in-2022/
Discuss your inventory funding needs with G-Force Funding. Approval and terms depend on lender review.
For more detail on collateral eligibility and monitoring, see the OCC’s Asset-Based Lending handbook. You can also compare our business line of credit guide.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Term Loans: Repayment, Costs and Key Questions
Updated September 30, 2026.
A business term loan provides an agreed amount of financing that is repaid over a defined period. The rate may be fixed or variable, and the payment schedule depends on the agreement. Do not assume every term loan has equal monthly payments or the same permitted uses.
When a term loan may fit
A defined purchase or project can be easier to evaluate when its cost and expected benefit are known. Match the repayment period to the project’s useful life and cash flow. Borrowing for ongoing losses requires a credible plan to address the underlying shortfall.
Understand the repayment structure
- Fully amortizing: Scheduled payments are designed to repay the balance by maturity.
- Balloon structure: A larger balance may remain due at the end. Confirm how you would pay it.
- Variable rate: Interest and payments may change under the agreement.
- Frequent payments: Daily or weekly withdrawals can affect cash flow differently from monthly payments.
Compare usable proceeds and total cost
Request the amount received after upfront charges, the complete payment schedule and all fees. Compare APR where provided, along with its assumptions. Ask about origination, closing, late-payment and early-repayment charges.
Illustrative example: A $50,000 loan with a $1,000 fee deducted upfront supplies $49,000 in cash. If scheduled payments total $57,000, the difference between those payments and cash received is $8,000. Payment timing still matters when comparing annualized costs. These figures are an example, not an offer.
Review collateral and guarantees
Determine which assets secure the loan and whether an owner guarantee applies. Ask about restrictions on selling assets or adding debt and how liens are released after repayment. See our secured business loan guide.
Prepare an application
Explain the funding purpose and provide the lender’s requested financial records, business information, existing debt schedule and project documentation. Eligibility and timing vary; there is no universal revenue or credit-score threshold for all term loans.
Compare alternatives
For recurring short-term funding needs, consider a line of credit. For equipment, compare loans and leases. For eligible projects, review SBA programs.
Discuss term financing with G-Force Funding or call (305) 563-4361. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Equipment Financing Examples by Industry
Equipment needs vary by industry. These examples can help you prepare a project list for a financing discussion; they do not mean every item qualifies under every lender’s program. Separate equipment purchases from inventory, subscriptions and building improvements before requesting an offer.
Construction and manufacturing
Examples include excavators, forklifts, fabrication machinery and power tools. Identify the jobs the equipment will support, expected utilization, transport costs and maintenance requirements. For used machinery, request condition and service records.
Retail and point-of-sale equipment
Retail projects may include checkout terminals, scanners, display fixtures and security equipment. Confirm compatibility with existing systems and include installation and training in the budget. Stock for resale is inventory, which may require a different financing product.
Restaurant and kitchen equipment
Ovens, refrigeration, dishwashers and food-preparation equipment can be central to a restaurant’s operations. Include delivery, ventilation, electrical work and any required installation approvals in the project plan. Ask which related costs the provider can finance.
Office and technology equipment
Computers, printers, networking hardware and office furniture may be part of an equipment project. Software subscriptions and ongoing support are different from a one-time hardware purchase. Ask how the provider treats licenses, installation and recurring charges.
Specialized professional equipment
Dental chairs, diagnostic devices, automotive lifts and other specialized assets require careful evaluation. Check servicing, warranties, staff training and any operational requirements before borrowing. A specialized asset may have a limited resale market.
Commercial vehicles and trailers
Delivery vans, work trucks and trailers can support transportation needs. Compare mileage expectations, payload, insurance, maintenance and lease return conditions. Additional vehicles increase capacity only if there is sufficient demand and staffing to use them.
Energy systems and building improvements
HVAC systems and other installed assets may be part of a broader improvement project. Roofing, insulation and structural work should not automatically be classified as equipment. Ask the provider whether the project requires equipment financing, real-estate financing or another structure.
Build a realistic project budget
- List each asset and obtain a vendor quote.
- Separate equipment, consumables, installation and ongoing costs.
- Estimate useful life and expected operational benefit.
- Compare financing payments with available cash flow.
- Confirm eligible assets, collateral and guarantees with the provider.
Use our equipment cost checklist to assess the purchase, then compare equipment loans and leases.
Discuss your project
Explore equipment financing with G-Force Funding or call (305) 563-4361. Ask whether an application involves a credit inquiry. Eligibility, terms and funding time depend on the provider’s review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Equipment Financing Options: Compare Loans and Leases
Equipment financing helps a business spread the cost of machinery, vehicles or other business assets over time. Compare the purchase price, financing cost, ownership terms and expected useful life before choosing a product.
Equipment loan or lease: what changes?
An equipment loan finances a purchase and typically gives the lender a security interest in the equipment. A lease gives your business use of equipment under a contract. Ownership, purchase options and return requirements depend on the agreement.
Neither structure guarantees zero upfront cost or freedom from personal guarantees. Ask about deposits, advance payments, liens, insurance, maintenance and end-of-term obligations. A low monthly payment can leave a substantial final payment or buyout cost.
Five equipment financing options to compare
1. Equipment loans
Compare offers tied to the specific equipment you intend to buy. Ask whether the provider finances used equipment and includes delivery, installation and taxes. Down payments, rates, amounts and terms vary by provider and borrower.
2. Equipment leases
A lease may suit a business that needs equipment for a defined period or expects to replace it regularly. Review return conditions, early-termination charges and any purchase option. Ask who pays for repairs and whether payments continue during downtime.
3. Business term loans
A business term loan may fund an eligible equipment purchase as part of a wider project. Compare the total cost and security requirements with a dedicated equipment loan. There is no universal revenue or credit-score threshold across all lenders.
4. SBA-backed financing
The SBA 504 program can support eligible long-term machinery and equipment with at least ten years of remaining useful life. It cannot fund working capital or inventory. A Certified Development Company can explain project eligibility and financing structure.
The SBA 7(a) program also includes eligible equipment purchases. Ask a participating lender which program fits your project and what documents, borrower contribution and repayment terms apply.
5. A line of credit or business credit card
For smaller purchases with a clear short-term repayment plan, compare an existing credit facility. Confirm available credit, fees, payment requirements and any promotional-rate expiration. Borrowing short term for a long-lived asset can create repayment pressure. See our business line of credit comparison guide.
Compare offers using the same assumptions
- Cash price and total amount financed.
- Upfront payment, scheduled payments, fees and final buyout or balloon payment.
- Fixed or variable rate and early-payoff terms.
- Collateral, liens and personal guarantees.
- Maintenance, insurance and return obligations.
- Expected useful life and realistic resale value.
Ask for a written payment schedule and an annualized cost comparison where available. Have your accountant assess the tax treatment of the specific agreement; do not assume every loan payment is deductible.
Prepare for the next step
Use our equipment loan application checklist to organize your quote and business records. Explore equipment financing with G-Force Funding to discuss your project. Approval and terms depend on review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Is Equipment Financing Worth It? An 8-Step Cost Checklist
Equipment financing can preserve cash at the time of purchase, but it creates a repayment obligation. Before borrowing, compare the expected benefit of the equipment with its full purchase, operating and financing costs.
1. Identify the problem the equipment will solve
Describe the current bottleneck: downtime, expensive repairs, insufficient capacity or a service you cannot offer. An equipment purchase should solve a measurable business problem rather than simply replace a functioning asset with a newer model.
2. Compare repair, replacement and rental
Request written estimates for each realistic option. Include downtime and the risk of repeat repairs. A short-term rental may fit a temporary project; buying may fit sustained use. Compare a lease’s return conditions and purchase option with ownership.
3. Estimate additional cash generated
Project the extra sales the equipment can support, then subtract the added costs of delivering those sales. Do not treat revenue as profit. Use a conservative estimate of demand and include the time needed to train staff or reach full capacity.
4. Include all operating costs
Budget for installation, training, maintenance, insurance, consumables and disposal. For vehicles, consider fuel and servicing; for software, consider subscriptions, support and integration. Confirm which costs the financing provider will cover.
5. Test repayment against cash flow
Compare scheduled payments with the cash available after operating expenses and existing debts. A profit-and-loss statement measures income and expenses; a cash-flow statement tracks cash movements. They are not the same document.
Illustrative example: If a machine is expected to generate $2,000 per month after additional operating costs and its financing payment is $1,200, the projected monthly cash remaining is $800. If the benefit falls to $1,000, the same payment creates a $200 monthly shortfall. These hypothetical figures exclude tax effects and are not a financing quote.
6. Check useful life and exit costs
Consider whether the equipment will remain useful throughout the repayment term. Review any final balloon payment, early-payoff cost, lease buyout or return charge. Do not rely on an optimistic resale value to make an otherwise unaffordable purchase work.
7. Review collateral and guarantees
Identify all pledged assets and any personal guarantee. The equipment may secure the financing, but the agreement can impose additional obligations. Ask the provider to explain what happens if payments are missed.
8. Get tax advice before counting on a deduction
Tax treatment depends on the asset, timing, financing structure and applicable rules. Ask your accountant about depreciation and any available election before estimating savings. Do not assume a fixed deduction limit or that the entire loan payment is deductible.
Compare financing and prepare your records
Read our equipment financing comparison and application checklist. Contact G-Force Funding to discuss your project budget and timeline. Approval and terms depend on lender review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Equipment Loan Application Checklist for Business Owners
Preparing an equipment loan application starts with a clear project budget and records that explain how your business will repay the financing. Requirements vary by lender, so request its checklist before submitting documents.
1. Get a detailed equipment quote
Include the seller, equipment model, condition, price and expected delivery date. Separate delivery, installation, training, taxes and warranty costs. Ask the lender which costs can be financed and whether it has age or condition restrictions for used equipment.
2. Explain the business purpose
Describe what the equipment will do: replace an unreliable machine, increase capacity or support a new service. Estimate any additional revenue or cost savings using assumptions you can explain. Include downtime, maintenance and staffing costs when assessing whether the purchase makes sense.
3. Gather financial records
- Recent business bank statements.
- Current profit-and-loss statement and balance sheet.
- Tax returns if requested.
- A schedule of existing loans, leases and required payments.
- Cash-flow projections for the purchase and repayment period.
- Business registration and ownership information requested by the lender.
For a newer business, a lender may also request a business plan and details of the owner’s experience. Submit sensitive records only through the provider’s verified application channel.
4. Review credit and security requirements
Ask whether personal credit, business credit or both will be reviewed, and whether a credit inquiry will affect your score. Review relevant reports for inaccuracies. There is no single credit-score, revenue or operating-history requirement that applies to every equipment lender.
Identify the equipment or other assets pledged as collateral. Ask whether a blanket lien or personal guarantee is required and understand the obligations before signing. Processing credit card payments is not a universal requirement for an equipment loan.
5. Compare the full repayment obligation
Request the amount financed, upfront contribution, payment frequency, fees and total scheduled repayment. Check for a balloon payment, variable interest rate or early-payoff charge. Assess affordability after operating expenses and existing debt payments, including a scenario with lower-than-expected sales.
6. Confirm timing before placing an order
Ask what must happen before funds can be released, whether the lender pays the vendor directly and whether an inspection or proof of insurance is needed. An application or preliminary discussion does not guarantee approval or funding by a specific date.
Loan, lease or another option?
Read our equipment financing options comparison for differences between loans, leases and SBA-backed financing. A loan should not be described as an advance against future card sales; confirm the actual product in any offer.
Frequently asked questions
Do all equipment loans require a 20% down payment?
No single down-payment rule applies to all providers. The required contribution depends on the agreement, equipment and underwriting.
Are the payments tax deductible?
Tax treatment depends on the financing structure and your circumstances. Ask your accountant to distinguish principal, interest, depreciation and lease expense; do not assume the full loan payment is deductible.
Can I finance used equipment?
Ask the provider about eligible equipment age, condition, valuation and expected useful life. Obtain an inspection or maintenance history where appropriate.
Discuss your equipment purchase
Explore equipment financing or contact G-Force Funding with your quote, business stage and timeline. You can call (305) 563-4361. Approval and terms depend on lender review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
10 Types of Business Financing: Loans, Credit and Alternatives
Updated September 30, 2026.
Business funding includes loans, revolving credit and other financing arrangements. The distinctions matter because repayment, ownership, fees and guarantees differ. Compare the structure to the expense before comparing providers.
1. Business term loans
Borrow an agreed amount and repay over a defined period. Check fixed or variable rates, payment frequency and any balloon balance. See our term-loan guide.
2. SBA financing
SBA programs serve different eligible purposes through participating providers. Review 7(a), 504 and microloan differences. A government guarantee does not eliminate repayment obligations.
3. Business lines of credit
Draw within available limits and repay under the facility’s conditions. Review draw fees, renewals, reporting and collateral. Our credit-line comparison lists questions for providers.
4. Equipment loans and leases
Finance the use or purchase of eligible equipment. Ownership and end-of-term obligations differ between loans and leases. Compare equipment financing options.
5. Invoice factoring
Sell eligible receivables to a factor under agreed terms. Check reserves, fees, customer contact and recourse if invoices are not paid. Read our factoring guide.
6. Receivables financing
Use eligible receivables to support borrowing rather than assuming the invoices are sold. Review borrowing-base rules, collections and security requirements. Financing and factoring are not interchangeable.
7. Merchant cash advances
These are commonly structured around future business receipts. Review the actual contract, factor rate, remittances, reconciliation and guarantees. A factor rate is not an APR, and an advance should not automatically be described as a conventional loan.
8. Personal borrowing for business
Some personal products permit business use and others do not. Confirm permitted uses. The individual remains responsible under the agreement even if the business fails.
9. Business credit cards
Cards can support merchant purchases, subject to limits and issuer terms. Review guarantees, fees, purchase grace periods and the rate after any promotion. Compare cards with credit lines.
10. Microloans
Smaller loans may come with technical assistance. Eligibility and terms vary by provider. The SBA microloan program is one route to investigate; not every microloan is an SBA loan.
How to narrow the choices
Write down the funding purpose, amount, deadline and repayment source. Compare net proceeds, total cost, payment frequency, security and guarantees. There is no universal approval threshold or best product for all businesses.
Discuss financing with G-Force Funding or call (305) 563-4361. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Small Business Grants: How to Find and Evaluate Opportunities
Updated September 30, 2026.
Small-business grants generally support a defined purpose, location, activity or group of eligible applicants. Finding a program is only the first step: you must verify that it is open, that your business qualifies and that the permitted uses match your project.
Start with official program information
The SBA grants page states that SBA does not provide grants for starting and expanding a business. It describes specific funding areas and resources. Do not assume a general startup qualifies for federal grant funding.
For any opportunity found through a directory, article or social post, locate the sponsor’s current official announcement before applying. Older contest amounts and deadlines are not evidence of an open award.
Where to investigate
- Government opportunities: Review official notices and confirm that for-profit businesses are eligible; many awards target other types of organizations.
- State and local economic-development programs: Ask about location, project and job-related conditions.
- Research and innovation programs: Check the current solicitation’s technical goals, ownership and application requirements.
- Private sponsors and business associations: Verify deadlines, membership requirements, selection criteria and permitted spending.
- Small Business Development Centers: Seek guidance identifying resources and preparing a business plan; assistance does not guarantee a grant.
Use an eligibility checklist
- Is the application window currently open?
- Does the sponsor accept your business type, location and stage?
- What expenses are allowed, and when may they be incurred?
- Are matching funds, reimbursements or milestones required?
- What records and reporting must you maintain?
- What conditions could require funds to be returned?
Prepare a focused application
Match your project to the sponsor’s stated purpose. Provide an itemized budget, achievable timeline and evidence supporting the expected results. Explain how you will fund costs that the award does not cover. Avoid generic applications that leave eligibility or outcomes unclear.
Do not rely on an award before it is confirmed
Grant competitions can take time and funding is not guaranteed. Keep a backup plan for essential expenses. Do not sign commitments that depend on an award unless you can meet them if the application is declined.
Be cautious of claims that payment guarantees a grant. Verify who operates the program and use its official application channel.
Compare grants with other funding
A loan creates a repayment obligation; equity funding shares ownership; grants have their own conditions. Our startup funding-source comparison explains the differences.
If you want to discuss business financing, contact G-Force Funding or call (305) 563-4361. A financing inquiry is not a grant application or promise of an award.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Small Business Bookkeeping: A Practical Weekly and Monthly Routine
Updated September 30, 2026.
Small-business bookkeeping records transactions and organizes the evidence behind them. A consistent routine helps you understand cash flow, prepare financial statements and answer questions during a financing application. Software can assist, but records still need review.
Set up a system suited to the business
Choose an accounting method and bookkeeping system with advice appropriate to your business and tax obligations. Cash and accrual methods differ in timing, and the choice is not simply a matter of preference for every business. Keep business transactions clearly identified and documented.
The IRS recordkeeping guide explains why supporting records matter and links to information about retention. Requirements depend on the type of record and circumstances.
A weekly bookkeeping routine
- Collect invoices, receipts and payment records.
- Review imported bank and card transactions for duplicates or incorrect categories.
- Send customer invoices and follow up on overdue amounts.
- Review upcoming supplier, payroll, tax and debt payments.
- Check cash available against the next few weeks of obligations.
A monthly review
Reconcile bank, credit-card and loan balances to statements. Investigate unexplained differences. Review receivables and payables aging, record necessary adjustments with your accountant, and prepare financial reports using a consistent period.
A profit-and-loss statement summarizes income and expenses for a period; a balance sheet shows assets, liabilities and equity at a date. Neither should be treated as a substitute for a cash-flow forecast showing when money will arrive and leave.
Keep debt records clear
Maintain balances, payment schedules, interest and fee records, maturity dates and collateral information. Separate loan proceeds from sales revenue and loan principal repayments from interest expense using the appropriate accounting treatment. Ask your accountant about unfamiliar transactions.
Work effectively with a bookkeeper or accountant
Define who enters transactions, reconciles accounts, reviews reports and handles tax work. Check qualifications for the services you need. Agree on deadlines, access controls, backups and how questions will be resolved. Outsourcing does not remove the owner’s need to review the results.
Prepare for financing
Lenders may request current financial statements, bank records, tax returns and a debt schedule. Consistent bookkeeping makes those records easier to gather and explain. It does not guarantee approval or shield an owner from liability under a guarantee.
Use our loan application checklist when organizing a funding request. For planning, review our business growth financial checks.
Discuss financing needs with G-Force Funding or call (305) 563-4361.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Financing Resources for Minority-Owned Businesses
Updated September 30, 2026.
Minority-owned businesses can compare mainstream financing with community lenders and business-support resources. Ownership status alone does not establish loan eligibility, a particular rate or approval. Start with your funding purpose, repayment capacity and the current requirements of each provider.
Compare financing structures first
A term loan, credit line, equipment loan or receivables-based arrangement creates different costs and obligations. Use our business financing overview to identify structures that fit the expense before choosing providers.
Community development financial institutions
CDFIs serve community-development purposes and may provide relevant financing or support. They include different types of institutions, not only nonprofit loan funds. The CDFI Fund’s information page explains the sector. Check a provider’s service area, products, application requirements and technical assistance directly.
SBA programs and participating lenders
Review 7(a), 504 and microloan options according to your project. These programs have their own requirements and are not automatic minority-business awards. Obtain current information rather than relying on old lender rankings or discontinued program terms.
Counseling and business support
The SBA’s business growth resources include information for minority-owned businesses and connections to counseling. A counselor can help review a plan, organize financial information and identify resources. Counseling does not guarantee financing.
Separate certifications, contracts, grants and loans
A certification is not itself a loan or grant. Contracting programs have separate eligibility rules, and obtaining certification does not guarantee a contract. Review the current SBA certification information before deciding whether to apply; do not assume identity alone establishes eligibility.
For grants, verify the sponsor’s official announcement, eligible applicants, permitted uses and current deadline. See our grant evaluation checklist. An old list of award amounts does not establish that money is available now.
Prepare questions for every provider
- Does the product serve your business location, industry and operating stage?
- What credit, revenue and documentation requirements apply?
- How much cash will you receive after fees?
- What are the payment schedule, total cost, collateral and guarantees?
- What application costs or credit inquiries apply?
- Who makes the credit decision, and who will service the account?
Build the application around your business
Organize your funding purpose, financial records, existing debt and repayment forecast. If the business is new, review our startup readiness guide. Compare written offers without assuming a provider is best based solely on marketing directed at a demographic group.
Discuss financing with G-Force Funding or call (305) 563-4361. Availability, approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
How to Prepare for a Business Loan With Bad Credit
Applying for a business loan with bad credit requires careful preparation and a realistic repayment plan. A low credit score can limit your options, but eligibility also depends on the provider, your business finances and the product. Approval is never guaranteed.
Check the lender’s requirements before applying
Ask whether the lender reviews personal credit, business credit or both. Confirm its current requirements for operating history, revenue, cash flow and existing debt. There is no single credit-score cutoff that applies to all online lenders or business credit cards.
Prepare your application
- Review your credit information. Check the reports the provider uses and dispute inaccurate information with the relevant reporting company. Personal and business credit reports are different products.
- Organize business records. Have recent bank statements, financial statements, tax returns and an existing-debt schedule ready if requested.
- Explain the funding need. State the amount, intended use and expected source of repayment.
- Test affordability. Compare required payments with your available cash after operating costs and existing debt payments. Consider what happens if customer payments arrive late.
Funding sources to discuss
Community lenders and CDFIs
Community development financial institutions can include banks, credit unions, loan funds and venture capital funds; they are not all nonprofit lenders. Check each institution’s service area, products and eligibility criteria. The CDFI Fund’s official information explains the different institution types. CDFI status does not guarantee approval or a particular interest rate.
Microloan intermediaries
The SBA microloan program provides loans up to $50,000 through intermediary lenders. That is the program’s maximum, not its average loan size. The intermediary determines eligibility and terms; ask about credit requirements and available business assistance.
Other business financing providers
Compare written offers from providers that serve businesses with your operating history and financial profile. Ask which type of financing is offered. A loan, invoice factoring arrangement and merchant cash advance have different structures and should not be treated as interchangeable.
Compare the full cost of each offer
- Amount you receive after any upfront deductions.
- Total scheduled repayment, interest and fees.
- Payment frequency and any automatic withdrawals.
- Collateral, liens and personal guarantees.
- Early-payoff terms and whether paying early reduces the cost.
- What happens if revenue falls or a payment is missed.
Ask for an annualized cost comparison where available. A factor rate or flat fee is not the same as an annual percentage rate. Do not judge affordability from the advertised payment alone.
If your business is new
A limited operating history can further restrict financing options. Review our startup business funding guide to compare loans with other sources of capital. Avoid treating guaranteed-approval advertising as evidence of eligibility.
Questions to ask G-Force Funding
Bring your funding amount, business age, revenue information and existing debt obligations to the conversation. Contact G-Force Funding or call (305) 563-4361 to discuss which options may fit. Available terms depend on the provider’s review.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Startup Business Loan Rates: How to Compare Offers
Updated September 30, 2026.
The best startup business loan rate is the rate on an offer your business qualifies for and can repay, after accounting for fees and terms. An advertised starting rate is not a personalized quote. New businesses should compare written offers using the same funding amount and a realistic payment forecast.
Why startup loan quotes differ
Providers may consider credit, time in operation, revenue, owner investment, industry, collateral and the proposed use of funds. Different products also price risk differently. There is no standard startup rate or automatic eligibility after a set number of months.
Collect these figures for every offer
- Gross financing amount and cash received after upfront deductions.
- Interest rate and whether it is fixed or variable.
- APR or an annualized cost comparison, where available, and the assumptions used.
- Payment amount, frequency, number of payments and total repayment.
- Origination, draw, maintenance, closing and other fees.
- Early-payment terms, renewal conditions, collateral and guarantees.
Interest rates, APRs and factor rates are different
An interest rate describes the interest charged under the agreement. APR expresses an annualized borrowing cost using applicable charges and timing. A factor rate is a multiplier used to calculate a repayment amount; it is not an annual percentage rate. Ask the provider to explain its calculation in dollars.
Illustrative comparison: Two offers each advertise $25,000 in funding and $30,000 in repayment. If one deducts a $1,000 fee upfront, it supplies only $24,000. If repayment schedules also differ, the offers do not have the same annualized cost or cash-flow impact. Review both usable proceeds and payment timing.
Watch introductory and variable rates
For an introductory card offer, verify the eligible transactions, promotional end date, fees and rate afterward directly with the issuer. Calculate whether you can clear the balance before the promotion ends. For variable-rate financing, ask which index applies and model higher payments.
Compare products that fit the expense
A multi-year equipment purchase, a temporary collection gap and pre-launch marketing may need different structures. Start with our startup funding overview. For equipment, compare loan and lease options. For SBA financing, review startup 7(a) application planning.
Check affordability before choosing the lowest payment
Build a monthly cash-flow forecast with startup costs, operating expenses and existing debt. Test delayed launch, lower sales and slower customer payments. A longer term may lower each payment while increasing total cost. Avoid borrowing solely because the credit limit is available.
The FTC’s small-business financing discussion highlights the importance of understanding financing costs and disclosures.
Request a financing discussion
Prepare your funding amount, intended use, operating history and repayment plan. Contact G-Force Funding or call (305) 563-4361. Eligibility, approval and terms vary by provider.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
SBA 7(a) Loans for Startups: Planning Your Application
Updated September 30, 2026.
An SBA 7(a) loan may be an option for an eligible new business, but it is not a grant or automatic startup funding. A participating lender evaluates the application under current SBA and lender requirements. Begin by asking whether the lender considers businesses at your stage of operation.
What the SBA guarantee means
The SBA provides a guarantee to the lender. It does not erase the borrower’s repayment obligation. The percentage guaranteed by the SBA is not the percentage an owner must contribute as a down payment. Ask the lender to state the required equity contribution separately and explain how it must be documented.
Check eligibility and permitted uses
The SBA’s current 7(a) overview explains business eligibility, permitted uses and the application process. It lists uses including working capital, equipment, real estate and eligible debt refinancing. The lender must confirm that your business and specific project qualify; a broad program description is not project approval.
Build a startup funding plan
- Itemize the project. Separate one-time setup costs from ongoing operating expenses. Support estimates with quotes, proposed leases or other records.
- Explain your contribution. Identify the funds already invested and the source of additional owner funds. Ask which contributions the lender will accept.
- Show repayment assumptions. Prepare sales, expense and cash-flow projections. Explain customer demand, pricing, hiring and the time needed to reach sustainable operations.
- Test a slower launch. Estimate how a delay or lower sales would affect payroll, rent and loan payments.
- Document experience. Explain who will operate the business and what relevant management or industry experience they bring.
Questions about rates, terms and fees
Request a written quote for your specific loan. Confirm whether the rate is fixed or variable, the base rate and margin if applicable, payment frequency, maturity, any balloon payment and prepayment conditions. Ask for all upfront and ongoing charges and who pays them.
Do not use an old online rate or annual fee schedule to budget a new application. A lower monthly payment can still produce more total interest when the repayment period is longer.
Collateral and guarantees
Ask which business or personal assets are pledged, who must guarantee the debt and what restrictions apply to further borrowing. Collateral and personal guarantees are different obligations. Our secured business loan guide explains the questions to review before signing.
Prepare for the lender’s review
The lender supplies the required document list. Organize business formation and ownership records, your business plan, financial projections, personal and business financial information requested by the lender, existing debt and supporting project documents. Ask about remaining approval conditions before committing to a purchase deadline.
The SBA directs applicants to participating lenders; its 7(a) program page also links to Lender Match and local assistance. Neither an inquiry nor a lender match guarantees approval.
If 7(a) financing is not a fit
Consider whether a smaller project, additional owner funding or another financing structure better fits the launch. Compare our six startup funding options, including microloans and non-loan alternatives, and review the obligations of each.
Discuss your financing needs with G-Force Funding or call (305) 563-4361. Product availability, approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Can Your Startup Qualify for a Business Loan? A Readiness Checklist
Updated September 30, 2026.
A startup may qualify for business financing, but a business plan alone does not guarantee approval. Providers differ in whether they consider pre-launch companies, newly operating businesses or only businesses with an established revenue history. Check that fit before preparing a full application.
1. Define your stage of business
State whether the business is an idea, legally formed but not trading, newly operating or acquiring an existing operation. Describe actual sales separately from forecasts. Ask the lender what operating history and revenue documentation it requires.
2. Calculate the funding gap
List setup expenses and the operating cash needed before customer receipts cover costs. Separate essential purchases from optional expansion. Subtract committed funds you can use without jeopardizing household necessities. Include fees and a reasonable contingency in the budget.
For example, if a project needs $40,000 and you have $15,000 available for it, the initial gap is $25,000 before financing fees or additional cash reserves. That calculation identifies a need; it does not determine an affordable loan amount.
3. Show how repayment would work
Prepare a cash-flow forecast explaining pricing, expected sales, collections, payroll, rent and other expenses. Include proposed debt payments and existing obligations. Test a delayed opening or lower sales. Explain the evidence behind your assumptions, such as signed contracts or documented market research.
4. Organize application records
- Business formation, ownership and licensing information.
- Business plan and relevant management experience.
- Project quotes, proposed leases or purchase agreements.
- Available bank records and financial statements.
- Personal and business financial information requested by the provider.
- Existing debts, proposed collateral and source of owner contributions.
A new business may not have business tax returns or a long trading history. Ask what alternatives the lender accepts; do not invent records or present forecasts as historical results.
5. Match the product to your situation
Compare our startup funding options before applying. Equipment finance requires an eligible purchase and underwriting. Receivables-based funding requires eligible receivables. Credit cards and personal borrowing can create owner liability even if the business fails.
If exploring SBA-backed financing, use our startup SBA 7(a) planning guide and confirm current eligibility with a participating lender. The SBA business planning resources can help develop the underlying plan.
6. Understand the offer before accepting
Confirm net proceeds, payment frequency, total repayment, fees, collateral, guarantees and approval conditions. Review our startup loan rate comparison checklist. Approval for more than your forecast supports is not a reason to borrow more.
What if you are declined?
Ask which requirements were not met and whether missing information could change the assessment. Consider a smaller launch, more time building sales or non-loan funding. Multiple applications do not solve an unaffordable repayment plan.
Discuss your startup funding needs with G-Force Funding or call (305) 563-4361. Approval, product availability and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Secured Business Loans: Collateral, Costs and Risks
Updated September 30, 2026.
A secured business loan is backed by collateral: assets pledged to support repayment. If the borrower defaults, the lender may enforce its rights against those assets under the agreement and applicable law. Collateral can affect an offer, but it does not guarantee approval, a lower rate or a longer repayment term.
Before borrowing, compare the repayment obligation with the assets at risk. A business that cannot support the payments may lose equipment, inventory or property it needs to operate.
How secured business loans work
The lender evaluates the business, the proposed use of funds, repayment capacity and acceptable collateral. It may request an appraisal or other valuation, review existing liens and limit the amount advanced against an asset. The amount you paid for an asset is not necessarily the value a lender will accept.
For an asset-based revolving line, availability can depend on a borrowing base of eligible receivables or inventory. Availability may fall when eligible assets decline, even if the stated credit limit stays the same. The OCC’s asset-based lending handbook explains borrowing bases, collateral monitoring and related risks.
Collateral, liens and personal guarantees are different
- Collateral is property pledged to secure an obligation, such as equipment, receivables or real estate.
- A lien or security interest gives the lender rights in the assets described by the agreement. A broad business-asset lien may cover several asset categories; read the actual scope.
- A personal guarantee is a separate promise by an owner or other guarantor to repay under its terms. It is not itself the same as pledging a specific asset. A lender may require both collateral and a guarantee.
Ask what assets are covered, whether existing lenders must consent and how the lender releases its lien after repayment. Have an attorney explain obligations you do not understand before signing.
Common secured financing options
- Secured term loan: A lump sum repaid on an agreed schedule, with specified collateral. Match the repayment period to the project and its expected cash flow.
- Equipment loan: Usually secured by the financed equipment, potentially with additional requirements. Compare ownership and lease alternatives in our equipment financing guide.
- Secured line of credit: Funds can be drawn subject to the facility’s limits and conditions. Review renewal, fees and collateral reporting in our line of credit comparison guide.
- Receivables or inventory financing: Availability may depend on eligible invoices or stock. Invoice factoring involves selling receivables and should not automatically be treated as a loan. Read our inventory financing overview.
- SBA-backed financing: Collateral and guarantee requirements depend on the program and loan. Check the SBA’s current 7(a) program information and ask the participating lender which requirements apply.
Potential benefits and risks
Pledging acceptable assets may expand financing options or support different terms. Compare actual written offers: a secured product is not automatically cheaper, and appraisal, filing, monitoring or closing fees can add to its cost.
The main risk is losing pledged assets following default. Selling collateral may not settle the entire debt; remaining liability depends on the documents and applicable law. A personal guarantee can create additional exposure. Restrictions on asset sales or further borrowing can also affect future business decisions.
How to compare offers
- Check usable proceeds. Compare the amount received after upfront fees with the amount needed for the project.
- Compare costs on the same basis. Request the interest rate, APR where provided, itemized fees, payment schedule and total repayment. Ask whether the rate can change.
- Test cash flow. Include existing debt and model slower collections or lower sales. A lower payment over a longer term can still mean greater total cost.
- List every obligation. Review collateral, guarantees, reporting, insurance, covenants, prepayment terms and default provisions.
- Check timing. Ask what remains before approval and funding, including valuation, title or lien review. Do not assume an advertised timeline applies to your application.
Application preparation
Prepare business and ownership details, a clear use of funds, financial statements, bank records, tax returns if requested, an existing debt schedule and cash-flow projections. For collateral, gather ownership records, asset descriptions, valuations and existing lien details. The lender’s checklist controls what is required.
Our collateral preparation guide can help organize the asset information. If you are comparing security requirements, read secured versus unsecured business loans.
Frequently asked questions
Can a startup or business with bad credit qualify?
Possibly, but collateral alone does not establish eligibility. Lenders assess the product’s requirements, repayment prospects and other application details. Avoid any offer that presents approval as guaranteed.
How much can I borrow?
The amount depends on the product, lender, business finances and acceptable collateral. There is no single maximum or standard advance percentage for all secured business loans.
Will borrowing improve my credit?
That depends on reporting practices and account performance. Ask which business or personal credit bureaus receive reports. Taking out a loan does not guarantee a higher score.
Discuss your financing needs
Have your funding purpose, requested amount and repayment plan ready. Contact G-Force Funding about financing options or call (305) 563-4361. Availability, approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Using Real Estate as Business Loan Collateral: Costs and Risks
Updated September 30, 2026.
Real estate may be accepted as collateral for business financing, but having equity does not guarantee a loan. The lender must evaluate the property, existing debt, proposed use of funds and repayment plan. Pledging property can put it at risk if the business defaults.
What does it mean to use real estate as collateral?
The owner grants the lender security rights in the property under the loan documents. The form of the real-estate security instrument and enforcement rules depend on the jurisdiction. Do not assume a general business UCC filing alone explains the rights being granted in land or a building.
A personal guarantee is a separate obligation. Ask whether the transaction requires both a property lien and an owner guarantee, and have an attorney explain the documents before signing. Our secured business loan guide explains the broader distinctions.
Property equity is not the same as available funding
A lender may require an appraisal and title review, apply a loan-to-value limit and account for existing liens. It may decline certain property types or lien positions. There is no universal percentage available against every property.
Illustrative calculation: A property valued at $500,000 with $300,000 of existing mortgage debt has $200,000 of equity before transaction costs. If a hypothetical lender limits total secured debt to 70% of value, the calculation is $350,000 less the existing $300,000, leaving $50,000 before fees and other restrictions. That is not an approval or an offer.
Questions about existing mortgages
- Does your current agreement allow another lien or require consent?
- Will the proposed lender accept its lien priority?
- Must an existing loan be paid off at closing?
- What are the closing, appraisal, title, recording and legal costs?
- What happens if the property’s appraised value is lower than expected?
Compare repayment terms and exit plans
Ask whether the loan amortizes fully or leaves a balloon payment at maturity. If repayment relies on a property sale or refinancing, test what happens if that plan is delayed or unavailable. Include existing property payments, taxes, insurance and operating expenses in your cash-flow forecast.
Compare written rates, fees, payment frequency, total repayment, prepayment provisions and default terms. Real-estate collateral does not automatically make an offer inexpensive. A daily or weekly automatic debit describes a payment method or schedule; it is not a separate category of loan.
Business property and personal property carry different consequences
Losing a business location could disrupt operations. Pledging a home can also threaten housing security. Review those consequences with the owners and a qualified adviser before committing property. Do not rely on projected growth alone to justify payments.
Documents to prepare
Ask the lender for its checklist before paying for third-party reports. It may request ownership and entity records, property details, existing mortgage statements, financial statements, tax returns, bank records, a debt schedule and an explanation of the funding purpose. Appraisals, title work and other due diligence can affect timing.
Consider the purpose of the financing
If the need is specifically an equipment purchase, compare equipment financing options. For recurring working-capital needs, review business lines of credit. Different products carry different security requirements, so compare actual offers.
Discuss your business financing needs with G-Force Funding or call (305) 563-4361. Product availability, acceptable collateral and approval depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
How to Get a Small Business Loan: A Step-by-Step Guide
Updated September 30, 2026.
To get a small business loan, define the funding need, check product eligibility, prepare records and compare written offers. Following a clear process can reduce unnecessary applications, but it does not guarantee approval or a particular rate.
1. Define the amount and purpose
Explain what the money will pay for and when you need it. Use quotes, contracts or a working-capital budget to support the amount. Separate essential expenses from optional growth spending. Determine how repayments fit alongside existing debt and operating costs.
2. Choose the type of financing to investigate
A term loan may suit a defined project. A line of credit may suit recurring short-term funding gaps. Equipment financing addresses eligible assets, while SBA-backed products have program-specific requirements. See our business financing types overview to compare structures.
For a new business, start with the startup readiness checklist. A lack of operating history changes the evidence available to a lender.
3. Check eligibility before applying
Ask each provider about minimum operating history, revenue, credit, industry restrictions and geographic availability. There is no single threshold that applies to every business loan. Ask whether the initial check affects personal or business credit and whether your application will be shared with other providers.
Review our six common business loan assessment areas to organize this conversation.
4. Gather the lender’s requested records
The required list varies. Common requests include business and ownership information, bank statements, financial statements, tax returns, a debt schedule, proposed collateral and the funding purpose. A startup or acquisition may require additional forecasts and project records.
Check that dates and totals agree across documents. Our business loan application preparation guide covers organizing the package.
5. Compare complete written offers
- Net cash received after upfront deductions.
- Interest, APR where provided, fees and total repayment.
- Payment amount, frequency and term.
- Collateral, guarantees and default provisions.
- Early repayment, renewal and additional borrowing restrictions.
- Conditions still required before funding.
Compare similar amounts and schedules. The lowest payment is not always the lowest total cost, and the fastest advertised funding is not always available for your application. Ask for unclear charges or terms to be explained in writing.
6. Review the agreement and track the loan
Before signing, confirm the final documents match the offer you evaluated. Have an adviser explain obligations you do not understand. After funding, record due dates, reporting requirements and contact information for servicing questions.
If declined, ask why and address the specific issue before applying again. A smaller request or stronger repayment plan may be more useful than submitting the same application to many providers.
Start a funding conversation
Contact G-Force Funding or call (305) 563-4361. Bring your funding purpose, requested amount and repayment plan. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
SBA Loan Programs: Compare 7(a), 504 and Microloans
Updated September 30, 2026.
SBA financing includes several programs with different purposes, providers and eligibility rules. The right starting point is the use of funds: working capital, equipment, property or a smaller business expense. An SBA guarantee is not a grant and does not remove the borrower’s repayment obligation.
Compare three common SBA programs
- 7(a): Participating lenders provide financing for eligible purposes such as working capital, equipment, property and certain refinancing or ownership changes. Review the current 7(a) program.
- 504: Designed for eligible major fixed assets, such as qualifying real estate or equipment. It is not general working-capital or inventory funding. Review the 504 program and discuss the project with a Certified Development Company.
- Microloans: Approved intermediary lenders make smaller loans under their own application requirements. Review the SBA microloan program for permitted uses and participating lenders.
Check the specific eligibility rules
Ask the provider to review your business type, ownership, location, size, use of funds, repayment ability and other current program requirements. Do not apply a credit score or time-in-business threshold from an old article to every SBA product. Lender underwriting also matters.
Separate the guarantee from your obligations
The government’s guarantee supports the lender. You still owe the debt, and collateral, owner contributions or personal guarantees may apply. A guarantee percentage does not establish your down payment. Get those requirements in writing and review unclear terms with an adviser.
Prepare a complete application
Request the provider’s checklist. Organize business and ownership records, financial statements, tax returns if required, bank records, existing debt and project documents. For a new business, prepare supported forecasts and a clear launch budget. Our startup 7(a) guide covers that preparation.
Review rates, fees and timing
Use a current written quote for the specific product. Confirm fixed or variable interest, all charges, payment frequency, maturity, prepayment provisions and conditions before funding. An SBA processing response is not the same as cash being available.
Temporary pandemic-era payment relief, fee waivers and limits should not be assumed to apply to new loans. Existing borrowers should use the SBA’s COVID-era program resources for those programs.
Choose the next step
Read whether a 7(a) loan fits your business or compare other business financing structures.
Discuss financing needs with G-Force Funding or call (305) 563-4361. Availability, approval and terms depend on the program, provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Construction Business Financing: Equipment, Cash Flow and Projects
Updated September 30, 2026.
Financing a construction company and financing construction of a property are different needs. A contractor may need equipment or working capital, while a property project may need staged construction funding. Define which need you have before comparing lenders.
Equipment for a construction business
For an eligible equipment purchase, compare loans, leases and renting. Include delivery, maintenance, insurance, operator training and expected utilization. The equipment may secure the financing, but additional guarantees or collateral can apply. Review our equipment financing options.
Working capital between project payments
Build a project-level forecast that shows labor, materials, subcontractor payments and expected customer receipts. Account for retainage, disputed change orders and delays. A line of credit may address eligible timing gaps, subject to its conditions.
If considering receivables funding, ask whether progress billings, retainage and disputed invoices qualify. Do not assume every construction invoice is eligible for factoring.
Financing a property construction project
Ask the lender what project budget, plans, permits, contractor information and valuation it requires. Confirm how draws are approved, what inspections or documentation are needed and whether funds are advanced or reimburse costs already paid.
Review who covers overruns, how delays affect the loan and what happens at completion or maturity. A plan to refinance requires its own underwriting; future refinancing is not guaranteed.
SBA-backed alternatives
Eligible projects may warrant a discussion of 7(a) financing or 504 financing for qualifying fixed assets. The 504 program is not a general working-capital facility. Ask the provider to confirm project eligibility, owner contributions and current terms.
Build a complete project budget
- Direct materials, labor and subcontractor costs.
- Equipment purchase or rental and operating expenses.
- Permits, design, professional services and insurance.
- Interest, fees and any required reserves.
- Contingency for delays and overruns.
- Cash needed while waiting for customer or lender payments.
Compare obligations before accepting
Review net proceeds, payment schedule, total cost, collateral, guarantees, draw conditions, maturity and any balloon payment. There is no universal credit-score, down-payment or operating-history requirement for every construction financing product.
Discuss your project with G-Force Funding or call (305) 563-4361. Bring the project purpose, budget, timeline and repayment plan. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Loan Requirements: 6 Areas Lenders Review
Updated September 30, 2026.
Business loan requirements vary by lender and product. Credit, cash flow, operating history, existing debt, collateral and industry are common assessment areas, not a universal approval formula. Ask for requirements for the specific financing you are considering.
1. Credit history
A provider may review personal credit, business credit or both. Scores use different models and scales. Ask which reports matter, whether the application creates a hard inquiry and what issues could prevent approval. A score mentioned in an old lender comparison is not a current lending commitment.
2. Revenue and cash flow
Revenue is not the same as cash available for repayment. Prepare records showing collections, operating expenses and existing payments. Explain seasonal patterns or unusual transactions. Compare proposed payments with a forecast that includes slower sales or collections.
3. Time in business
Providers may require a particular operating history or consider startups under separate criteria. Ask how the lender measures time in business and what documentation it accepts. New businesses may need projections, project details and owner experience in place of a long financial history.
4. Existing debt
Prepare a debt schedule listing balances, payment frequency, maturity dates and security. Include credit lines and other financing obligations. A lender may calculate coverage or leverage ratios using its own definitions; there is no single ratio threshold for every product.
5. Collateral and guarantees
For secured financing, describe proposed assets, ownership, estimated value and existing liens. An asset’s purchase price may differ from the lender’s accepted value. Personal guarantees are separate from collateral and may apply to some unsecured products. See our secured loan guide.
6. Industry and business eligibility
Ask about industry, geographic, legal-entity and permitted-use restrictions before preparing a full application. Government-backed programs also have program-specific requirements. Read our SBA program overview if relevant.
How to use this checklist
For each provider, write down the requirement, your supporting record and any unanswered question. Do not confuse meeting minimum criteria with approval. Underwriting may consider additional information and conditions.
Next, organize documents using our application preparation guide. New businesses can use the startup readiness checklist; owners concerned about credit can review bad-credit financing considerations.
Discuss your funding needs with G-Force Funding or call (305) 563-4361. Availability, approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Is a Business Line of Credit Right for Your Business?
Updated September 30, 2026.
A business line of credit can help manage a temporary difference between expenses and receipts. It is most useful when the business understands why it needs a draw and how it will repay it. An available limit is not the same as cash reserves or guaranteed future funding.
Identify a temporary need
Examples include buying seasonal inventory before sales arrive or paying a supplier before customers settle invoices. Build a forecast showing the expected draw, repayment source and timing. If the balance keeps growing to cover recurring losses, investigate the operating problem before adding more debt.
Understand how this particular line works
Some facilities revolve as principal is repaid, subject to their conditions. Others attach a repayment schedule to each draw. Ask about the draw period, maturity, renewal, minimum draw, payment frequency and conditions that could reduce or suspend access.
Compare interest and fees
Interest commonly applies to drawn funds, but maintenance, draw, origination or renewal fees may apply even when borrowing is limited. Request an itemized schedule and written examples based on the amount and duration you expect to use. If the rate varies, ask what causes changes and model higher payments.
Test a repayment scenario
Illustrative example: A business draws $15,000 for inventory and expects to repay from sales in three months. Model slower sales taking six months, including additional financing costs and regular operating expenses. Confirm the facility actually permits the planned repayment schedule.
Review collateral, guarantees and reporting
Ask which assets are pledged, whether owner guarantees apply and what financial reports you must provide. For an asset-based line, borrowing availability may change with eligible collateral. Read our secured financing guide for these distinctions.
Compare alternatives for the expense
A long-lived purchase may warrant a term loan. Routine merchant purchases may warrant a credit-card comparison. Supplier payment arrangements or better collections may reduce borrowing needs.
Questions before opening a line
- What requirement would prevent approval or renewal?
- How much would your planned use cost in dollars?
- Can you repay under a slower-sales forecast?
- What fees apply if you leave the line unused?
- Can the provider reduce availability, and under what conditions?
- How and when are guarantees or liens released?
Use our line of credit lender comparison guide to evaluate offers. Contact G-Force Funding or call (305) 563-4361 to discuss your needs. Approval and terms vary by provider.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Line of Credit vs. Business Credit Card
Updated September 30, 2026.
A business line of credit and a business credit card both offer access to credit, but they can serve different expenses. A line often provides funds that can be transferred to a business bank account. A card is primarily designed for payments to merchants that accept it. Compare the actual fees and repayment rules before choosing either.
Key differences to check
| Feature | Business line of credit | Business credit card |
|---|---|---|
| Access | Draw funds using the lender’s process, subject to availability. | Pay accepting merchants; cash advances may have separate costs. |
| Payments | May be daily, weekly or monthly; some draws have their own repayment schedule. | Statement payments follow the issuer’s agreement. |
| Fees | Possible draw, origination, maintenance or renewal fees. | Possible annual, late, cash-advance or other transaction fees. |
| Security | May require collateral and a personal guarantee. | Guarantees may apply; some cards require a security deposit. |
When to consider a line of credit
A line may fit a temporary gap between supplier payments and customer collections, especially when an expense cannot be paid by card. Check permitted uses and how quickly draws become available. A revolving limit is not a promise of permanent access: renewals, financial reviews and collateral conditions can affect it.
Read our business line of credit comparison guide for lender questions.
When to consider a business credit card
A card may fit routine purchases that your business can repay according to the agreement. Check whether a purchase grace period applies and what conditions preserve it. Do not assume cash advances receive the same rate or grace period as purchases.
Review introductory offers directly with the issuer, including the end date and subsequent rate. Rewards and benefits vary; interest and fees can outweigh their value. Do not spend more simply to earn a welcome bonus.
Compare the same expense under both offers
For a planned purchase, record the amount needed, when you will repay it and the total cost under each option. Include merchant surcharges, draw fees, cash-advance charges and annual fees where relevant. If the expense is a long-lived asset, also compare equipment financing.
Check owner liability and credit reporting
Ask which credit reports the provider reviews, whether applying creates a hard inquiry and which bureaus receive payment history. A business account does not automatically keep the owner free of personal liability. Read guarantees and default provisions before signing.
Can a business use both?
Yes, but the combined payments must fit the business’s cash flow. Keep track of all balances, renewal dates and payment obligations. Using one facility to cover another’s payments repeatedly can hide a growing cash shortfall.
Discuss your funding needs with G-Force Funding or call (305) 563-4361. Approval, availability and terms vary by provider.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Line of Credit Options: How to Compare Lenders
A business line of credit can help cover inventory, payroll timing and other short-term cash-flow needs. The best option depends on the total borrowing cost, repayment schedule and requirements your business can meet.
Updated October 5, 2026. This guide replaces the original 2021 lender comparison. Confirm current pricing and eligibility directly with each lender before applying.
How a business line of credit works
A line of credit lets you draw funds up to an approved limit. With a revolving line, repaid principal can become available to borrow again, subject to the agreement. A term loan instead provides a lump sum with a repayment schedule. Review the line’s renewal conditions, draw period and repayment rules before relying on it for recurring expenses.
Business line of credit options to compare
- Banks and credit unions: Ask your existing financial institution about its business credit products and the documents it needs to assess your application.
- Online lenders: Compare the complete payment schedule and fees, including the cost of each draw. A fast application does not guarantee approval or immediate funding.
- SBA-backed working capital programs: The SBA’s 7(a) program includes working capital financing options. An SBA-approved lender can explain which program fits your circumstances and whether you qualify.
There is no single best lender for every business. Compare written offers for the same amount and expected repayment period rather than choosing by the advertised credit limit alone.
Compare offers using the same borrowing scenario
Choose a draw amount and an expected repayment period before comparing lenders. Ask each provider for a written payment schedule for that scenario. A credit limit tells you how much you may be able to access; it does not tell you the cost of using it.
| Compare | What to request | Why it matters |
|---|---|---|
| Cash received | The amount deposited after any withheld fees | Equal draw amounts can provide different amounts of usable cash. |
| Repayment schedule | Every payment amount, frequency and due date | Daily or weekly withdrawals can affect cash flow differently from monthly payments. |
| Total dollar cost | Total scheduled payments plus separately paid fees, minus net cash received | This provides a comparison for the stated scenario. It is not an APR calculation. |
| Unused credit | Maintenance fees, renewal requirements and suspension conditions | Access to unused funds may depend on ongoing requirements. |
| Early payoff | A payoff example and any fees that remain due | Paying early may not eliminate every financing charge. |
| Security | Required collateral, liens and personal guarantees | Understand the obligations attached to the proposed credit. |
A simple dollar-cost example
Suppose an illustrative offer provides $20,000 in cash and requires $21,200 in payments, with a $300 fee paid separately. The borrowing cost for that scenario is $1,500. If the $300 fee is already included in the payments, do not add it again. Compare offers over the same period and account for payment timing; this example is not a lender quote or an annualized rate.
If you need one amount repaid over a defined term, use our SBA loan payment calculator to explore an amortizing term-loan scenario. It does not model revolving credit draws. If you are replacing existing obligations, read our business debt refinancing guide to compare remaining payments, fees and total cost.
Questions to ask before accepting an offer
- What will this draw cost in dollars? Request a payment schedule showing principal, interest and fees. Ask for an annualized cost comparison where available.
- Which fees apply? Check for origination, draw, maintenance, renewal and late-payment charges.
- When are payments due? Confirm whether payments are daily, weekly or monthly, and compare the required withdrawals with your expected cash flow.
- Can the price or limit change? Ask about variable rates, renewals and circumstances in which access to unused credit can be reduced or suspended.
- Does early repayment reduce the cost? Request the payoff terms in writing; do not assume every fee disappears when you repay early.
- What security is required? Identify any collateral, business-asset lien or personal guarantee and understand your obligations before signing.
What lenders may review
Requirements vary by lender and product. There is no universal minimum credit score, revenue level or time-in-business threshold for every business line of credit. Ask for the lender’s current criteria before submitting an application.
Prepare recent business bank statements, financial statements, tax returns and a list of existing debts if requested. Write down how much you need, what you will use it for and how your business expects to repay it.
Secured and unsecured credit lines
A secured line is backed by collateral. An unsecured product may still require a personal guarantee; the product name alone does not explain every obligation. Ask the lender to identify any pledged assets, liens and guarantees in the proposed agreement.
When another financing option may fit better
A recurring short-term funding gap is different from a large purchase that will support the business for several years. Compare a line of credit with a term loan when you know the full amount needed up front. For everyday purchases, compare business credit card terms as well, including any cash-advance costs.
Frequently asked questions
Do I pay interest on the entire credit limit?
Interest is generally associated with the amount borrowed, but separate fees may apply even when you are not using the full line. Check the agreement’s pricing and fee schedule.
Can a new business qualify?
Eligibility depends on the lender. A limited operating history can restrict your options. Ask about time-in-business requirements and avoid assuming that a published minimum means approval is guaranteed.
How do I choose an affordable credit limit?
Start with your expected funding gap and a realistic repayment plan. Test whether your cash flow could support payments if sales arrive later than expected. An approved limit is not a recommendation to borrow the full amount.
Explore funding with G-Force Funding
Start a business funding application to discuss your needs with G-Force Funding. Available products, approval and terms depend on your business and the lender’s review.
Further reading: Review the SBA’s official 7(a) loan overview and the Federal Reserve’s explanation of small-business credit products and costs.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Examining the Tax Implications of PPP Loans
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. The Paycheck Protection Program ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
For existing-loan assistance, consult the SBA’s official COVID-era program resources and your lender. For a new financing need, compare our business credit guide or startup funding options.
Original historical article
Even if the loan is forgiven, expenses paid with a PPP loan might be deducted on your taxes.
The Paycheck Protection Program ended on May 31, 2021. For additional information, see our PPP Loan Forgiveness Guide.
For business owners who obtained a loan under the Paycheck Protection Program, the approaching tax season has raised new questions. Answers to these queries have been difficult to come by, in part because of the IRS’s fluctuating advice. However, new guidelines stated out in the most recent round of coronavirus treatment assist to clear things up.
Doing your taxes was difficult for most before COVID. The good news is that this year’s tax returns won’t be any more difficult than previous years.
PPP loans that have been forgiven are not taxable.
If you have a business loan and it is forgiven, that is automatically taxable income in the past and in the future. It’s always been in the internal revenue code up to this point. Loans through the Paycheck Protection Program are an exception to this rule. Forgiven PPP loans will not be counted as income, according to Congress and the IRS. This is true whether your full loan or a portion of it is forgiven.
If it is forgiven, it will not be taxable income.
You can deduct expenses incurred as a result of a PPP loan.
It’s been a bit of a moving target with this one. The IRS formerly said that expenses paid with PPP loan funds could not be deducted if the loan was or would be forgiven.
That changed on Dec. 27, 2020, when the coronavirus relief legislation was enacted into law, stating that deductions should not be prohibited just because the debt was forgiven.
This means that any expenses incurred as a result of your PPP loan are tax deductible. This result effectively generates two tiers of tax benefits for PPP loan recipients. The first benefit is making the loan income-tax-free. The second is allowing businesses to claim income deductions on expenses paid
PPP funding cannot be used to pay for business taxes
The most recent round of coronavirus relief also allows business owners greater options when it comes to how they use PPP funds. Protective equipment, property damage, and business software are among the new costs covered.
Taxes on businesses are not included in the expanded list. As a result, if you use your PPP loan to pay your business taxes, you will not be forgiven that amount.
The Employee Retention Tax Credit is still available.
If your business meets the requirements, you can now claim the Employee Retention Tax Credit. There is one crucial caveat: salaries paid with a forgiven PPP loan cannot be claimed.
You can, however, claim the credit on salaries paid in excess of the forgiven amount.
To be eligible for the tax credit, you must continue to pay employees despite being temporarily closed due to COVID-19 limits or experiencing a 20% decline in gross receipts from the previous year’s comparable quarter.
The coronavirus relief bill ushered in these changes on Dec. 27, 2020, but they are retroactive to March 12, 2020. The credit is valid for eligible wages paid up to July 1, 2021.
Apply today with G-Force Funding for business loans from $10,000 – $500,000.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Our Guide To PPP Loan Forgiveness
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. The Paycheck Protection Program ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
For existing-loan assistance, consult the SBA’s official COVID-era program resources and your lender. For a new financing need, compare our business credit guide or startup funding options.
Original historical article
Millions of small business owners who took out Paycheck Protection Program loans are now eligible for loan forgiveness.
Despite the uncertainty, delays, and problems experienced by many small company owners in obtaining a Paycheck Protection Program loan, having the debt forgiven may prove to be surprisingly, refreshingly simple.
Borrowers with loans in the range of $150,000 or less are exempt from having to demonstrate receipts. Most of the time, all you have to do is tick a box confirming that you met the PPP requirements for payroll costs and eligible expenses. (For second-draw loans, you must also show a qualifying revenue loss.)
This is where the great majority of PPP debtors fall. 95% of the almost 6.7 million PPP loans provided in 2021 were for less than $150,000. In 2020, 87 percent of all PPP loans will be for less than $150,000.
While you have no control over the amount of your loan — that is determined by a formula established by the US Small Business Administration — you can have power over other aspects that make loan forgiveness simpler.
Relationships are important.
John Sims got his PPP loan through Chase, where he also has a business checking account and knows his business banker by first name (he was even in a book club with one of his bankers).
When he applied for his loan and for forgiveness, that relationship made all the difference. Despite just qualifying for a few thousand dollars at a time when Chase was granting PPP loans of more than $100,000 on average, he had his banker’s ear.
Keep a COVID file
Jill Peters began a COVID-19 file to store all relevant information when the pandemic shut down her studio.
She explains, “I have an MFA in ceramics; I’m not a very business-minded person when it comes to keeping track of those tiny bits and stuff.” “Having everything in one area was quite beneficial to me because I was able to quickly locate items without having to go through different locations.â€
Peters followed suit, putting together separate files (both digital and paper) with copies and scans to show how her PPP loan was used. Because of the simpler application, she didn’t have to supply those records for her loan forgiveness, but she has them on hand in case the loan is audited.
Do you have any questions? Rely on professionals.
Turn to professionals — your accountant, your lender, and the SBA — rather than internet armchair experts, as questions emerge.
There’s a lot of information out there, and things get shared around on social media like it’s a phone call,†Peters adds. “It’s helpful to know exactly what’s going on versus some third-party account on Twitter.”
Are you unsure about the terms of forgiveness or dealing with a non-responsive lender? The SBA offers webinars and counselors to assist with all PPP-related issues.
Apply today with G-Force Funding for business loans from $10,000 – $500,000.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
How to Apply for PPP Loan Forgiveness
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article

Learn when and how to apply for a PPP loan Forgiveness, as well as what expenses are covered.
Small businesses dealing with the coronavirus epidemic can take advantage of the Paycheck Protection Program, which offers 100% forgivable loans. However, applying for that forgiveness can be difficult, especially for small business owners with limited resources.
There is some good news: businesses that borrowed $150,000 or less can now use a simplified loan forgiveness application that requires no additional documentation for first-draw borrowers. For reference, till Aug. 8, 2020, when the first round of PPP loans completed, 87% of PPP loans provided were for less than $150,000.
To help business owners better understand the PPP loan forgiveness procedure, we’ve put up a guide.
PPP Loan Forgiveness Requirements
For first- and second-draw PPP loans, the loan forgiveness standards are the same. Maintaining staffing and compensation levels during the covered period is required to receive full loan forgiveness.
Additionally, during the covered time, money from your PPP loan must be spent on approved expenses (see below). At least 60% of your loan must be spent on payroll costs in order for it to be fully repaid.
Most loans made in 2020 are insured for 24 weeks after they are disbursed, however borrowers who received their loans before June 5, 2020, can keep the initial eight-week duration. In 2021, business owners who receive a first- or second-draw loan can choose a covered term ranging from eight to 24 weeks.
Expenses eligible for loan forgiveness
Initially, only salary and operational costs were considered eligible, but the coronavirus relief bill passed in December 2020 expanded the list to include supplier costs, expenses for health and safety improvements, and some property damage.
PPP loan forgiveness is now available for the following expenses:
- All wages paid, including tips, commissions, and bonuses, as well as employer-paid benefits such as insurance, sick leave, and retirement contributions, are included in payroll costs. Employees who earn more than $100,000 per year are not eligible for compensation forgiveness.
- Mortgage payments and interest, rent, utilities, and business software such as accounting, payroll, and inventory management programs are all examples of operating costs.
- Supplier costs: If the purchase order or contract was in place before the covered period, the cost of products essential to operating your firm is eligible for forgiveness. Purchase orders for perishable commodities placed during the covered period qualify as well.
- Property damage: This is for repairs to property damaged or lost as a result of looting during public disturbances in 2020. Insurance-covered expenses are not eligible.
- Worker protection: Personal protective equipment and other costs connected to health and safety standards, such as health checks, barrier installation, or expanding outside eating, are included in this category.
There are a few details to keep in mind: costs incurred before the covered period but paid during the covered period are forgiven. Costs incurred during the covered period but paid after it ends are also covered, as long as they are paid by the following normal payroll or billing date.
When should you request for loan forgiveness under the PPP?
You can request for PPP loan forgiveness as soon as the funds have been spent or as late as your loan has matured. However, you should do so before making a single payment.
After the covered time (eight to 24 weeks) concludes, payments on PPP loans are postponed for ten months. If you petition for forgiveness after this date, you’ll have to start making payments on your loan.
Borrowers who petition after their loan matures, which is two years for loans issued before June 5, 2020 and five years for loans issued after that date, will not be eligible for forgiveness.
How to Apply for Forgiveness of PPP Loans
When you’re ready to apply for forgiveness, contact your PPP lender. They will be able to connect you to the appropriate loan forgiveness form. That, coupled with documentation demonstrating how you used the loan, must be submitted. It will be easier to apply for forgiveness if you collect this paper trail as you go. The sorts of documentation you may be required to furnish are listed below.
For first-draw loans of less than $150,000, business owners can use a simplified form and don’t need to provide any further documentation. Before a second-draw debt can be forgiven, borrowers must demonstrate the required revenue loss.
Documentation needed for PPP loan forgiveness
You must also provide proof of how you spent the PPP loan along with your loan forgiveness application. Only monies spent on permitted expenses will be forgiven, so keep that in mind. To qualify for complete forgiveness, at least 60% of your loan must be used for payroll expenses.
The documentation you’ll need to submit with your PPP loan forgiveness application are listed below. Note that this list is not complete, and not all documents will be required by all businesses.
Payroll Costs
- Quarterly financial reports from the state and local governments.
- State unemployment insurance filings.
- Bank statements
- Third-party payroll reports.
- Tax documents: Form 1040 Schedule C or Schedule F, Form 1065 Schedule K-1, Form 941, Form 944, Form W-2, and Form W-3
- Payment receipts, canceled checks, or account statements that demonstrate employer contributions to health and retirement plans.
Other costs
- Statements of account.
- Account statements.
- Utility bills that show that payments have been made.
- Purchase orders, contracts, and vendor payment receipts.
- Cancelled checks or invoices for covered expenses such as business software, protective equipment, safety upgrades, and repairs for damage caused by protests during the summer.
Apply today with G-Force Funding for business loans from $10,000 – $500,000.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Small Businesses Alternatives To PPP Loans
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article
Small business entrepreneurs have multiple competitive options for accessing funding when the economy recovers.
As the economy bounces back and the U.S. transitions out of the pandemic, small-business owners will need access to capital to both recover and grow. However, since federal relief from the Paycheck Protection Program ended on May 31, business owners may be wondering where to get financing or looking for new options after an unsatisfactory PPP experience with a particular lender.
The ideal funding source will always be determined by a company’s specific needs, credentials, and industry, among other things. Here are four possibilities to think about.
Community and regional banks
Small banks are known for their low interest rates, long durations, and large loan amounts, as well as customized service and quick decision-making. Their technology, on the other hand, has fallen behind that of other lenders. Nonetheless, bank small-business loans are still tough to obtain; applicants must have outstanding credit and solid financials.
While both big and small banks have been gradually increasing loan approval rates throughout 2021, Biz2Credit’s Small Business Lending Index report shows that they are still far from pre-pandemic levels  small banks approved 50.3 percent of small-business loan applications in February 2020, compared to only 18.9% in June 2021.
Small Business Administration
Standard SBA loans, such as the 7(a) loan, will continue to be effective funding options for small businesses even after the PPP program has ceased. SBA loans, like bank loans, can be difficult to obtain, but they come with long periods and low interest rates. The SBA enhanced the guarantee on 7(a) loans and waived ordinary loan fees in December 2020 to benefit small firms and encourage lenders to offer funding.Â
Online lenders
Although banks have made some technological advancements, online business loans can still provide a faster application and funding process. Despite the fact that banks typically have lower interest rates than online lenders business owners may be prepared to pay a little more for a more efficient service.
Fintech financing will approach pre-pandemic levels within the next three years, according to a forecast released by S&P Global Market Intelligence in February 2021. Small- and medium-sized business lenders, in particular, are forecast to boost loan originations by 16.2% by 2024, totaling $15.8 billion. Online lenders are also more likely to lend to start-up companies or those with fair or poor credit.
CDFIs and non-profit lenders
Nonprofit lenders and community development finance institutions, or CDFIs, can be excellent providers of low-cost credit, particularly for smaller loans. These mission-driven organizations are also excellent choices for underprivileged businesses, such as women- and minority-owned businesses.
CDFIs have launched low-interest lending programs to support business owners who were left behind by the PPP program during the pandemic.
The Southern Opportunity and Resilience Fund, for example, provides loans of up to $100,000 to help businesses get through the current crisis. However, capital isn’t the main objective of these initiatives. These programs also provide the support and mentoring that firms require in order to progress to other sorts of finance.
Apply today with G-Force Funding for business loans from $10,000 – $500,000.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
What Can You Do If Your Business Cannot Get a PPP Loan?
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article

Other SBA loans and grants from state and local agencies and organizations are available to small business owners. The Paycheck Protection Program ended on May 31, 2021. For additional information, see our PPP page or our PPP Loan Forgiveness Guide.
For businesses that qualify, the Paycheck Protection Program can be a lifeline, but it’s not the only option for those coping with the coronavirus pandemic. Those that do not meet the PPP standards may be eligible for grants and other finance, such as state and local grants and Small Business Administration loan programs.
Other Loans and grants from SBA
For failing businesses, the Small Business Administration offers numerous loan options. SBA-backed loans have lower interest rates and more favorable terms than private-lender loans, but applicants must still fulfill minimum credit requirements and may be required to put up collateral.
Economic Injury Disaster Loans
These low-interest loans, which were previously only available to businesses affected by natural disasters, are now available to businesses with up to 500 employees that can demonstrate a financial loss due to the coronavirus pandemic.
Eligible businesses can get up to $150,000 in working capital for up to six months. More than $25,000 in collateral is necessary. Operating expenses, such as fixed debt payments, can be paid with money borrowed through an EIDL. EIDLs are not eligible for loan forgiveness, unlike PPP loans, however payments are suspended for a year.
Microloans and SBA 7(a) Loans
The SBA provides a number of alternative loan programs for small-business owners who have been affected by the coronavirus. Your business needs and the specific loan program will determine how much you can borrow and in what circumstances.
Microloans, for example, have a maximum loan amount of $50,000. The maximum size of a standard 7(a) loan is $5 million. SBA Express loans, which are part of the 7(a) program, are ordinarily limited to $350,000, but the Economic Aid Act of late last year increased the maximum to $1 million from January 1 to October 1, 2021. After that, Express loans will have a maximum limit of $500,000.
Microloans cannot be used to refinance existing debt, for example, although 7(a) loans can. Working capital can be financed with funds from either loan program. These loans are not forgiven, but they qualify for the Small Business Administration’s debt relief program, which was recently expanded to include coronavirus treatment. On loans approved between February 1 and September 30, 2021, the SBA will cover the first six months of principle and interest.
Shuttered Venue Operators Grants
Operators of Shuttered Venues Theaters, live music venues, talent agencies, and select museums, zoos, and aquariums that can show a revenue loss of at least 25% are eligible for SBA grants. Some promoters and producers are also eligible.
The SVO grant program is relatively new, and applications are not being accepted at this time. Businesses that lost at least 90% of their revenue between April and December 2020 will get first dibs on grant awards once the program is open, followed by those that lost at least 70%, and finally all other qualifying businesses. These high-priority groups may be eligible for additional funding.
Qualifying sites are eligible for up to $10 million in funding, though most would receive far less. Depending on when your business started, the exact amount depends on sales, which is either 45 percent of 2019 gross income or average monthly gross revenue. The funds can be used for business expenses such as leases and mortgage payments, as well as worker protection, state and municipal taxes, and debt repayment.
Other grant programs
For businesses in need of capital, loans aren’t the only choice. Thousands of grants, including those granted by federal, state, and local government entities, are available to qualified small businesses.
Are you unsure where to begin your search for a grant? Try the chamber of commerce, the Small Business Development Center, or the Economic Development Administration office in your area.
Grants.gov and GrantWatch.com are two databases that provide a complete, searchable list of available grants (note: GrantWatch.com keeps grant details behind a paywall).
Applying for every grant under the sun is not the greatest way. Do your homework and apply for grants that are a good fit for both you and the funder.
Don’t waste your time applying for something you are not eligible for. Take the time to find out about what past grants the organization has funded and who won the awards. By learning all you can, you will have more context to frame your proposal and be better positioned for a win.
Most grants have strict guidelines and are generally tailored to a specific objective, location, business type, or demographic, such as veteran-owned or minority-owned businesses.
Apply today with G-Force Funding for business loans from $10,000 – $500,000.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Loans With Bad Credit: Options, Costs and Risks
Updated September 30, 2026.
Getting a business loan with bad credit may be possible, but eligibility and cost vary by provider. There is no universal minimum score, guaranteed approval or single “best” loan for every business. Compare the amount you need, the payments you can support and the obligations in each written offer.
What lenders may review besides credit
Personal and business credit are different. A lender may review one or both, alongside revenue, cash flow, time in business, existing debt, industry and collateral. A startup with little operating history may need projections and evidence of the owner’s experience or investment. Strong sales do not automatically offset every other requirement.
Ask which credit report and scoring model the provider uses and whether checking eligibility involves a soft or hard inquiry. Avoid treating a score quoted in an old article as an approval threshold.
Financing options to compare
Term loans
A term loan provides a lump sum with scheduled repayments. Compare the repayment period, payment frequency, fees and total cost. Short repayment periods can create substantial cash-flow pressure even when the requested amount is modest.
Business lines of credit
A line may provide flexible access to funds within agreed limits. Interest commonly applies to the amount drawn, but draw, maintenance, renewal or other fees may also apply. Review the conditions for continued access in our business line of credit guide.
Equipment financing
Equipment may support financing for its purchase, but it does not eliminate underwriting or guarantee approval. Ask about down payments, additional collateral, personal guarantees and repossession risk. Compare equipment loans and leases.
Receivables financing and factoring
Receivables financing uses eligible invoices to support borrowing. Factoring generally involves selling receivables to a factor. Check fees, customer notification, collection responsibilities and what happens if a customer does not pay. These structures should not be treated as interchangeable.
Community lenders and microloans
Some community lenders offer smaller loans and business support. Requirements still apply. The SBA microloan program operates through approved intermediaries; ask the intermediary directly about eligibility, permitted uses, collateral and guarantees.
Merchant cash advances
MCAs are commonly structured around future business receipts and may use a factor rate rather than an APR. Review remittance frequency, reconciliation provisions, fees and guarantees. A factor rate is not an annual interest rate. The FTC discusses cost and disclosure concerns in small-business financing.
Compare cost using actual cash flows
Request the net amount you receive, all required payments, total repayment, itemized fees and any early-payment adjustment. Ask for an APR or annualized comparison where available, together with the assumptions used.
Illustrative example: A $20,000 advance with a 1.30 factor produces $26,000 of stated repayment before additional fees. That does not mean a 30% APR: the timing of payments and amount actually received matter. Compare a complete payment schedule, not just a percentage in an advertisement.
Questions to ask before applying
- What minimum requirements apply to this specific product?
- Will the application be shared with other providers, and who will contact you?
- Which assets or personal guarantees support the obligation?
- Are payments affordable after existing debt and essential operating expenses?
- What happens after a missed payment, early repayment or drop in sales?
- Are quoted funding timelines conditional on underwriting and documentation?
Get written answers. Claims of guaranteed approval or no risk should prompt closer review of the provider and agreement.
If you are not ready to borrow
Review your reports for errors, keep financial records current and develop a realistic repayment forecast. Ask a declined lender what prevented approval before submitting more applications. Delaying a purchase, reducing the project scope or improving collections may reduce the amount you need.
For an application checklist, read how to prepare for a business loan with bad credit. If the business is new, compare our startup funding options.
Discuss your business funding needs
Contact G-Force Funding about financing options or call (305) 563-4361. Approval, availability and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Is an SBA 7(a) Loan Right for Your Business? A Decision Checklist
Updated September 30, 2026.
An SBA 7(a) loan may fit a business with an eligible funding purpose and a workable repayment plan. It is not automatically the cheapest, fastest or most suitable choice. Compare the proposed loan with alternatives using your project, timing and obligations.
Does your project fit the program?
The SBA’s 7(a) overview lists permitted uses and current eligibility criteria. Ask a participating lender to confirm that your exact project qualifies. A working-capital request, equipment purchase, property project and ownership change can require different documentation.
Can the business support repayment?
Prepare a cash-flow forecast with the proposed payment, existing debt, taxes and essential operating expenses. Test a slower-sales scenario. If a loan simply postpones an ongoing operating loss without a credible recovery plan, reconsider the amount or project before borrowing.
Does the timing work?
Ask what remains before approval and disbursement, including underwriting, valuations and closing documents. Do not equate an expedited program response with a guaranteed funding date. Make purchase commitments with the actual financing conditions in mind.
Are you comfortable with the security requirements?
Request a written explanation of collateral, personal guarantees, required owner contributions and restrictions on further borrowing. The SBA guarantee protects the lender under program rules; it does not cancel your obligation to repay. It also does not determine your down payment.
Our collateral and guarantee guide explains the distinctions to discuss with an adviser.
Have you compared the complete cost?
- Amount received after closing costs and upfront charges.
- Interest rate, fixed or variable terms, and possible payment changes.
- Payment schedule, term and total repayment.
- Prepayment provisions and fees.
- Reporting, insurance and other ongoing obligations.
Use a current quote. Old rate tables, temporary fee waivers and expired pandemic relief do not establish terms for a new application.
What alternatives should you review?
A fixed-asset project may warrant a 504 discussion; a smaller need may warrant a microloan discussion. Our SBA program comparison explains those starting points. Also compare suitable conventional loans or a smaller project funded from available cash.
Prepare for the conversation
Bring the funding purpose, budget, financial records and existing debt schedule. New businesses can use our startup 7(a) planning checklist.
Discuss your financing needs with G-Force Funding or call (305) 563-4361. Approval and terms depend on the provider, program and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Loan Collateral: A Preparation Checklist
Updated September 30, 2026.
Using collateral for a business loan starts with documenting what you own, what it is worth and whether another lender already has rights in it. A lender decides which assets it will accept and how much financing they support. Collateral does not guarantee approval.
This checklist helps prepare for a lender conversation. For definitions and product types, see our secured business loan guide.
1. Create an asset list
List the proposed collateral, legal owner, location, purchase date, current condition and supporting records. Possible categories include equipment, vehicles, eligible receivables, inventory, real estate or deposit accounts. Availability varies by lender and product; do not assume every asset qualifies.
- Equipment and vehicles: Gather invoices, serial numbers, titles where applicable and maintenance records.
- Receivables: Prepare an aging report showing customers, amounts due, due dates and disputed or overdue invoices.
- Inventory: Record quantities, cost, condition, location and slow-moving or obsolete stock.
- Real estate: Gather ownership, mortgage, tax, insurance and property information requested by the lender.
2. Identify existing claims
List outstanding debts and liens associated with each asset. Existing loan documents may restrict additional borrowing or pledges. Ask the proposed lender whether it requires first priority, another lender’s consent or a payoff. An existing lien is not automatically removed by applying for new financing.
3. Confirm the valuation method
Purchase price, book value, market value and liquidation value can differ. Ask which value the lender uses, whether it requires its own appraisal, who pays the cost and how long the valuation remains usable. Avoid ordering an appraisal before confirming the lender’s requirements.
Illustrative example: If a lender accepts an asset value of $100,000 and applies a 70% advance rate, that calculation supports $70,000 before other limits, existing claims or fees. This is an example, not a standard rate or financing offer.
4. Understand ongoing monitoring
For some asset-based facilities, the amount you can borrow changes with eligible collateral. Ask about reporting deadlines, inspections, exclusions, reserves and what happens if availability falls below the outstanding balance. The OCC’s asset-based lending handbook explains these monitoring concepts.
5. Assess what your business could lose
Identify whether the proposed collateral is essential to daily operations. Default may lead to enforcement against pledged assets, and a sale may not eliminate the remaining debt. Personal guarantees create separate obligations. Review any proposal involving a home or other personal property carefully with a qualified adviser.
6. Compare the complete offer
Request the amount received after fees, payment schedule, rate, total repayment, appraisal and filing charges, early repayment terms and all guarantees. Ask how liens will be released after repayment and what restrictions apply to selling assets or borrowing elsewhere.
Prepare a forecast that includes existing debt and lower-than-expected sales. The ability to pledge an asset is not a substitute for a workable repayment plan. Our secured versus unsecured loan comparison covers questions to ask across offers.
Prepare for your funding conversation
Bring your asset list, debt schedule, business financial records and intended use of funds. Discuss options with G-Force Funding or call (305) 563-4361. Each provider sets its own documentation and eligibility requirements.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Invoice Factoring: Advances, Fees and Recourse Explained
Updated September 30, 2026.
Invoice factoring generally involves selling eligible business receivables to a factor to receive cash before customers pay. It differs from receivables financing that uses invoices to support borrowing. The agreement determines fees, reserves, collection responsibilities and what happens when an invoice is unpaid.
How the advance and reserve work
A factor may advance part of the invoice amount and retain a reserve until collection and settlement. The advance percentage affects immediate cash, while fees and settlement rules affect the final proceeds. Neither the advance rate nor the fee alone tells you the full value of the arrangement.
Illustrative example: On a $10,000 invoice, an 80% advance supplies $8,000 initially and leaves a $2,000 reserve. If the customer pays in full and the agreed fee is $300 with no other deductions, the remaining settlement is $1,700. Total proceeds are $9,700. These figures illustrate the mechanics, not available terms.
Understand every charge
Ask whether fees are fixed or increase with time, which amount they apply to and whether there are minimum volume, setup, transfer, servicing or termination charges. Compare net proceeds for prompt payment and late-payment scenarios. A percentage factoring fee is not automatically an annualized interest rate.
Clarify customer contact and collections
Ask whether customers are notified, where they send payments and who handles disputes. Check whether your customer contracts permit assignment and what records the factor needs. Customer creditworthiness, invoice age, concentration and disputes may affect eligibility.
Recourse and non-recourse terms
Under recourse terms, you may have to repay or replace an unpaid invoice. A non-recourse label does not necessarily cover every reason for nonpayment; exclusions and conditions matter. Review chargebacks, disputes, fraud provisions, guarantees and any security interests with an adviser.
Decide whether factoring fits your cash cycle
Compare the cost with the benefit of earlier cash and with alternatives such as improved collections or a business line of credit. Factoring does not solve a pricing or profitability problem by itself.
Prepare an aging report, customer list, invoice records, payment history and existing financing details. Ask whether the contract covers selected invoices or a broader receivables portfolio.
Discuss receivables funding with G-Force Funding or call (305) 563-4361. Availability, eligibility and terms vary by provider.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
8 Ways to Build and Maintain Business Credit
Updated September 30, 2026.
Business credit is not a single score used by every lender. Reporting agencies and scoring models differ, and providers may also review an owner’s personal credit. These eight practices can help maintain accurate records and responsible payment habits; none guarantees a score increase or loan approval.
1. Review relevant business credit reports
Ask prospective providers which reports they use. Check business identity details, accounts, balances and payment information. The SBA’s business credit report overview explains common report information.
2. Correct genuine inaccuracies
Use the reporting agency’s process to dispute information that is wrong. Keep supporting records and track the response. Do not dispute accurate information merely because it is unfavorable or expect legitimate negative information to disappear immediately.
3. Pay obligations as agreed
Maintain a due-date calendar and payment reminders. If using automatic payments, monitor balances and transactions. Contact the provider early if a payment problem arises; a conversation does not change the contract unless new terms are agreed.
4. Keep borrowing manageable
Track revolving balances and available limits. Avoid relying on additional borrowing to cover ongoing losses. Consider cash-flow impact before opening accounts or increasing balances solely to build credit.
5. Ask whether suppliers report payments
A supplier relationship does not automatically appear on a credit report. Ask whether, where and how the supplier reports. Use trade terms only for purchases your business needs and can repay.
6. Keep business information consistent
Maintain accurate legal names, addresses and ownership records across your accounts and business documents. Reconcile bookkeeping records so you can explain your business’s finances when applying for credit.
7. Review personal credit where relevant
Some lenders assess owner credit or require guarantees. Ask about inquiries and reporting before applying. Personal and business credit models are different, so do not treat an improvement in one score as assurance about another.
8. Review accounts deliberately
Evaluate fees, security, usefulness and borrowing needs before opening or closing an account. There is no universal rule to keep every old card open regardless of cost. Ask how a change may affect reporting and your ability to manage payments.
Connect credit habits to financing readiness
Lenders may also assess cash flow, operating history, collateral and existing debt. Read our business loan requirements guide and application preparation guidance for owners with credit concerns.
Discuss financing needs with G-Force Funding or call (305) 563-4361. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Loan Application Checklist: Documents and Preparation
Updated September 30, 2026.
A useful business loan application tells a consistent story: what the money will fund, how the business operates and how it will repay. Start with the lender’s document checklist, then reconcile the records before submitting them.
Write a clear funding summary
State the requested amount, intended use, timing and expected benefit. Attach quotes or project records where relevant. Explain the repayment source and distinguish confirmed sales from projections.
Organize financial records
- Current financial statements, including a profit-and-loss statement and balance sheet.
- Bank statements for the periods requested.
- Business and personal tax information if required.
- Receivables and payables aging reports where relevant.
- A debt schedule showing balances, payments and maturity dates.
- A cash-flow forecast with the proposed loan payments.
Check that names, dates and totals agree across records. Explain unusual deposits, one-time expenses or gaps rather than leaving the reviewer to guess. Do not change historical records to make performance look stronger.
Review credit information
Ask whether the provider reviews personal or business credit and whether an inquiry affects your score. Review relevant reports for inaccuracies and use the reporting agency’s dispute process for genuine errors. A credit report and a credit score are not the same thing, and different sources may contain different information.
Prepare business and ownership documents
Gather formation and ownership records, licenses and relevant leases or contracts requested by the provider. If the loan involves equipment, property or an acquisition, request the project-specific checklist. Submit sensitive records only through the provider’s verified secure process.
Document collateral and guarantees
List proposed collateral, ownership records, existing liens and any valuations available. Ask which owners must guarantee the debt. Our collateral checklist can help prepare this information.
Test repayment capacity
Include all existing debt and essential expenses in a consistent-period forecast. If a lender uses debt-service coverage, ask how it defines cash flow, which obligations it includes and what threshold applies. Avoid using a universal ratio from an online article as proof that you qualify.
Test slower sales, delayed collections and unexpected expenses. Improving collections or negotiating agreed supplier terms may help cash flow; simply allowing bills to become overdue creates additional problems.
Complete a final review
Confirm the application is complete and accurate, keep a copy, and track follow-up requests. Get written clarification of rates, fees, security and conditions before accepting an offer. A complete application can reduce avoidable delays but does not guarantee approval.
For the broader process, read how to get a business loan. Contact G-Force Funding or call (305) 563-4361 to discuss your needs.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Business Debt Refinancing: Compare Savings, Costs and Risks
Updated September 30, 2026.
Refinancing replaces existing debt with new financing. Consolidation combines obligations and may be part of a refinance. Neither automatically lowers the total cost, improves credit or solves a cash-flow problem. Compare the remaining cost of your current debts with the complete proposed replacement.
Start with payoff information
Request current payoff statements and expiration dates. Identify prepayment charges, remaining scheduled payments, lien-release requirements and any existing guarantees. A balance shown on a statement may not equal the amount required to close an account.
Compare payments and total cost separately
A longer repayment period may lower each payment while increasing total interest. A lower advertised rate may be offset by closing costs or fees. Compare the same remaining debt and note any extra cash included in the new loan.
Illustrative example: If existing scheduled payments total $24,000, and a replacement loan would require $25,000 in payments plus $1,000 paid separately at closing, the replacement costs $2,000 more in total. It might change monthly cash flow, but it is not a total-cost saving. Avoid counting a fee twice if it is already financed into the quoted payments.
Review what changes besides the rate
- Payment frequency and maturity date.
- Fixed or variable interest and possible future changes.
- Collateral, personal guarantees and lien priority.
- Balloon payments, covenants and reporting obligations.
- Prepayment provisions and renewal conditions.
Check whether the proposed product permits refinancing
Not every provider will refinance every obligation. For SBA-backed financing, eligible refinancing must meet program and lender requirements; do not assume all cash advances or other debts qualify. Review the SBA 7(a) overview and have the lender assess the actual debt.
Test your cash-flow forecast
Include all payments that will remain after closing. If the refinance provides relief, identify how you will address the underlying shortfall. Avoid assuming that moving debt guarantees an improved credit score or future access to funding.
Before closing
Confirm which accounts will be paid off, who sends the payments, whether any balances remain and how releases will be documented. Compare the final agreement with the offer and get advice on unclear obligations.
Read our term-loan guide for repayment structures. Discuss refinancing needs with G-Force Funding or call (305) 563-4361. Eligibility, approval and terms vary by provider.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Will Your PPP Loan Be Audited?
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article

On Saturday July 4, 2020, President Donald Trump signed a new law extending the deadline for applying for a Paycheck Protection Program (PPP) loan from June 30 to August 8. This extension comes on the heels of new Interim Final Rules (IFR) released by the Small Business Administration (SBA) on June 22, clarifying some issues and attempting to make complete loan forgiveness possible for most borrowers.
In addition, on July 6, 2020, the SBA and the Treasury Department released the complete database of all PPP loans issued to date– roughly 4.9 million. For loans exceeding $150,000, the data includes company name, address, NAICS codes, demographic information, date the loan was issued, number of employees, and congressional district. For loans less than $150,000, the name and address were left out.
In a July 6 press release issued by the SBA, Treasury Secretary Steven T. Mnuchin specified, “The average loan size is approximately $100,000, demonstrating that the program is serving the smallest of businesses.” He added that, “Today’s release of loan data strikes the appropriate balance of providing the American people with transparency, while protecting sensitive payroll and personal income information of small businesses, sole proprietors, and independent contractors.”
The release of the data came at the request of many groups and politicians seeking transparency for the $650 billion loan program created under the CARES Act. There is apprehension among some that the program is subject to widespread fraud and misuse, and they desire accountability. Already, many companies receiving negative press coverage and fearing audits and penalties returned $30 billion in PPP funds, although arguably they received them legitimately under the guidelines.
On the other side of the debate are many business groups who want to see a “safe harbor” that all borrowers who received the loans, or at least those under a specific threshold such as $1 million, will receive loan forgiveness for portions of the loan they use according to regulations– 60% on payroll and 40% on expenses such as rent, mortgage payments, utilities, and interest payments on loans.
The release of the data caused immediate apprehension among borrowers as the data seemed incomplete. After reviewing the data, many companies were reported having none or one employee, even though their loan amounts exceeded $150,000, signaling many more employees. This raised considerations that inaccurate data would cause audits or adversely impact a review. The reality is the data demonstrates the input from lenders who were working around the clock to issue the loans as fast as possible and, as per the CARES Act, gave borrowers the benefit of the doubt that the loans were necessary and employees were to be kept on the payroll.
For most borrowers, the inaccurate data will be of no consequence. Businesses with 10 or fewer employees, sole proprietors, or independent contractors will not be the target for harsh reviews or audits, and while those borrowers who received over $2 million in PPP funds have a much higher likelihood of audit, the real targets will consist of fraudsters lying on loan documents.
While the program has been filled with complications, confusion, and new regulations being released almost weekly, the reality is, it has had the desired effect of injecting liquidity into the economy and maintaining workers on the payroll. While approximately $130 billion remains in the program, necessitating the extension to August 8, the federal government moved at an unprecedented pace and scale on this program. Considering that the SBA issues about 1,000 loans in a typical year, 4.9 million PPP loans in three months is commendable.
The fact that funds remain is the result of a slowdown in applications as many borrowers were worried that audits would leave them keeping a loan they thought would become a grant, or worse, civil or criminal penalties. So, in addition to the extension, the new guidance from June 22 was also meant to assuage the worries of many businesses and increase applications.
While it remains to be seen whether the new guidance will boost loan applications over the next month, the new guidance and future regulations sure to come still create as many questions as they seek to answer. Here are some of the most frequently asked questions on PPP loans and forgiveness: https://gforcefunding.com/ppp-loan-forgiveness-6-26-2020/
Should I be worried about an audit on my PPP loan?
The new guidance did not provide any specific safe harbors for an audit. The SBA already provides a safe harbor, whereby loans less than $2 million will be considered made in good faith based on economic uncertainty, so there will not be much reason to audit these loans. With government mandated shutdowns, ongoing cases of COVID-19, and a rocky reopening of the economy, economic uncertainty remains for all businesses.
The main concern with audits of loans over $2 million will remain the issue of the “credit elsewhere” test and the liquidity of the borrower. Unlike traditional SBA loans, business owners didn’t have to document a lack of credit elsewhere, and only certify if they did not have sufficient access to credit. At this point, it appears that short of venture funding available or access to public capital markets by virtue of a stock exchange listing, most companies that are audited will likely be able to reasonably claim a lack of adequate credit elsewhere, even with traditional lines of credit.
What can I expect next for any easing of restrictions on PPP loans?
The main issue still remaining in the program is around taxes. PPP loans do create adverse tax consequences, mainly that expenses, including federal payroll taxes paid by the employer with PPP funds, are not deductible. So, while PPP funds that are forgiven are not taxable, businesses will lose these deductions.
Business groups are lobbying intensely to make changes to PPP, especially on the payroll tax issue, in what’s being called Phase 4 legislation. The new law could also offer new funds focused on certain demographics or allow companies a second PPP loan. Negotiations for the new law are underway and should conclude before the Congressional August recess.
Conclusion
The extension of the PPP program until August 8 and the new guidelines should incentivize more businesses to apply for loans. Despite the confusion, the program is largely functioning as designed, which is to provide small businesses with emergency funds to weather the coronavirus storm. While the possibility of an audit remains very real, there is likely more regulations to come that will, hopefully, explain and define what that looks like so businesses have the certainty they need.
In the meantime, with COVID-19 cases surging in many parts of the country, businesses may be facing a new wave of full or partial shutdowns. That prospect will likely accomplish two things: One, remove the issue of “economic uncertainty” from the discussion; and two, lead to a robust new package of economic stimulus.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
PPP LOAN FORGIVENESS – 6/26/2020
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article
If you’ve secured an SBA Paycheck Protection Program (PPP) loan, you’ve likely calculated your payroll costs and decided on how you will spend the funds to keep your business stable.
However, that is not the end of your required documents if pursuing loan forgiveness. There are necessary steps to take to bring in sure your PPP loan is completely– or partially– forgiven. Here is a breakdown of the forgiveness process so you can get a clear picture of your loan forgiveness obligations and make a list of specific questions. A good start in answering your questions is to look at the Treasury guidance issued May 5 and then talk to your banker and your accountant.
Is PPP loan forgiveness automatic or do I have to take action?
Paycheck Protection Program loan forgiveness is not automatic. You must submit a request for loan forgiveness through the lender you obtained for your PPP loan with. The application for forgiveness is due within 90 days of the expiration of the eight-week post-funding period. The approval process is expected to be completed within 60 days of the application.
Who is eligible for PPP loan forgiveness?
If you received an SBA PPP loan during the two rounds of funding, you are eligible. Forgiveness of SBA 7( a) loans or other funding received before or during the pandemic is not part of PPP forgiveness.
What is the process for PPP loan forgiveness?
Your lender will provide a form for loan forgiveness documentation, calculations and certifications for accuracy. Forgiveness calculation is based on the eight (8) week period from date of final loan disbursement (not the approval date).
Loan forgiveness details
Employers can apply for full or partial forgiveness if they spend their loans on qualifying expenses over the eight weeks after receiving a loan. Qualifying expenses include:
- Payroll costs (Business owners must spend at least 75% of their loans on payroll costs)
- Utilities
- Mortgage interest (not including principal payments)
- Rent
- For in-depth information of qualifying expenses and calculations, review the U.S. Treasury guidelines PDF
What documentation should I gather?
- Employee pay records for 2019 and 2020 by pay period (to assist with baseline wages before the covered period starts)
- Employee pay records for each week when the covered period starts
- FTE count for 2/15/2019 through 6/30/2019 and 1/1/2020 through 2/29/2020
- FTE count for each week when the covered period starts
- Supporting documentation for payments of non-payroll costs (invoices, checks, proof services in place prior to 2/15/2020)
Special rules for PPP loan forgiveness
- Loan proceeds are used to cover “payroll costs” (the same definition as the loan application), mortgage interest in place prior to 2/15/2020, rent paid on leases in place prior to 2/15/2020 and utility costs (generally electricity, gas, water, telephone, and internet) for services in place prior that are paid over the eight-week period that begins the date the loan is made (the “benefit period”)
- At least 75% of the loan proceeds must be used for payroll costs. The 75% spend on Payroll Costs Rule published by the SBA on April 2 directs that not more than 25% of loan forgiveness can be for non-payroll costs, hence 75% of forgiveness must be for payroll costs (likely subject to additional guidance)
Employee headcounts maintained
Compensation levels are maintained for employees earning $100,000 or less
What reduces PPP loan forgiveness amounts?
- If full time employees and compensation are restored, loan forgiveness reductions listed above may not be applicable according to the SBA you have until June 30, 2020 to restore your full-time employment and salary levels for any changes made between February 15, 2020 and April 26, 2020
- Compensation for individuals earning more than $100K annually
- Employees residing outside the United States.
- Qualified sick and family wages paid under the Families First Coronavirus Response Act (FFCRA) where the business may claim a credit
- There is an additional reduction calculation if you bring back workers but reduce their pay from the pre-pandemic time-period by more than 25%
What if I’m an independent contractor or sole proprietor?
PPP forgiveness is slightly different for sole proprietors and independent contractors. The biggest difference is “owner compensation replacement” which simplifies the loan forgiveness process.
The amount of “owner compensation replacement” you’re eligible to claim is calculated by multiplying your reported net income in 2019 on your Schedule C by 8/52 (or 0.154).
What happens if I don’t get full PPP loan forgiveness?
PPP loan terms are generous and offer the lowest-cost working capital around.
If you don’t get a portion of your loan forgiven, you’ll be responsible for paying back the loan with a 1% interest rate. PPP loan payments are deferred for six months and payable within 2 years.
What if I want to return my PPP loan?
May 14 was the deadline for returning funds is provided by the SBA for companies that received PPP funds but later found that they were unable to certify in good faith that their PPP loan was necessary. One reason to return the funds is if you feel like the forgiveness guidance is too stringent.
Are there other options for impacted businesses who did not receive PPP funding?
After PPP loan funds have been exhausted, there are options for small business owners without a PPP loan.
Term loans and other financing may be tough to get in this economic environment. However, the SBA 7( a) loan program will likely continue and is a low-cost option for businesses who qualify. You can apply today with G-Force Funding to be considered for an SBA 7( a ) loan.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
SBA PPP For Self Employed & 1099
Archived 2020 article: The Paycheck Protection Program ended on May 31, 2021 and is closed to new applications. The original discussion below reflects early program rules and is not current application, forgiveness or tax guidance. Visit the SBA’s official COVID-era program resources for information about existing loans.
The Paycheck Protection Program (PPP) was designed to support American small businesses with immediate cash support during the COVID-19 pandemic. If you are a sole proprietor, an independent contractor, or a gig worker, here’s what you need to know, and what you’ll need to apply.
Almost all small businesses qualify for the Payment Protection Program.
This includes:
- Sole proprietors who report income and pay taxes on a Schedule C in your personal tax return
- Independent contractors who collect 1099-MISC forms
- Gig economy workers who take on-call jobs provided by companies such as Uber, Lyft, and Instacart
The only restriction is that your business was operational before February 15, 2020. If you started your business after that date, you will not be eligible for this program.
What is the benefit of the Paycheck Protection Program?
This program was designed to help Americans remain employed and retain their salaries. As the name implies, this is a payroll-focused program. The payout you receive will be based on your average monthly payroll expense multiplied by 2.5. Under the PPP, your payroll expense can include your salary expenses and health insurance premiums.
The biggest benefit of this program is that it can be almost entirely forgiven. You do not have to pay tax on any portion of the loan being forgiven (meaning the loan becomes tax-free grant). If you keep your payroll expenses consistent to what they were before the COVID-19 pandemic for a further eight weeks, including the salary paid and the number of employees paid, you could be eligible to have those expenses forgiven from your loan amount, as well as certain other expenses such as rent and utilities.
The good news is that if you are self-employed (and you are your only employee), this should be easy to achieve.
However, it is important to note that you can not receive both Unemployment Benefits and a PPP loan at the same time. You should consider the payout of each program to determine which is the best fit for you.
What if I don’t use a payroll service?
If you own a business and do not give yourself a salary through a payroll service, you are likely still eligible for the Paycheck Protection Program – with one exception. Businesses that are structured as C corporations or S corporations must use payroll to pay their owners, because the corporation is taxed separately from the individual. If you own a corporation and have not been paying yourself a salary through payroll, you will not have a salary covered through the PPP This is because distributions or dividends from a corporation are not considered to be a salary or self-employment income.
Payments made to contractors aren’t considered payroll and aren’t eligible under the PPP.
Sole proprietors and the PPP
If you run a business on your own, your business is a sole proprietorship even if you haven’t formally let the IRS know.
Since you don’t have employees, you won’t be reporting your payroll costs for the PPP loan. Instead, you’ll be reporting your net business income, which will be reported on a Schedule C. As long as your business was operational prior to February 15 of this year, you can apply to the Paycheck Protection Program.
According to the U.S. Treasury, “regardless of whether you have filed a 2019 tax return with the IRS, you must provide the 2019 Form 1040 Schedule C with your PPP loan application.”
If you’ve already filed your taxes, this should be easy: just submit your filled-out Schedule C with your application. If you haven’t filed your taxes yet, you will likely need to get retroactive bookkeeping done so you can calculate your net income and fill out your Schedule C properly.
If you don’t have bookkeeping or a tax return, we strongly recommend that you get caught up with your bookkeeping. Without a payroll service, bookkeeping is the best way to determine your net profit as a sole proprietor (which is what the PPP will ask for).
Your monthly average payroll expense will be your annual net profit divided by 12. If your annual net profit is over $100,000, you may only claim up to $100,000 divided by 12.
Sole proprietors who are married
If you run a sole proprietorship informally with a spouse, you will only apply to the PPP once, and your spouse would not be considered to have a salary through the business unless he or she was paid as a contractor prior to February 15, 2020.
If you own more than one sole proprietorship, you may apply separately for each – but only if these sole proprietorships have separate EINs. The general rule of thumb is that you can apply separately for as many businesses you own that have separate identification numbers, or separate tax reportings. You may apply for the PPP once with your SSN as a sole proprietor, and then separately for any other businesses you own using their EINs.
Independent contractors and the PPP
If you work as a 1099 independent contractor, you are by default considered to be a sole proprietor in the eyes of the IRS. This means your freelance income gets reported annually on a Schedule C within your personal tax return. You will have a Schedule C even if you pick up odd jobs or do freelance work, and this Schedule is based on the 1099-MISC forms you collect from the companies or individuals who have hired you as a contractor.
Your salary is most easily determined by looking at the net profit listed on your Schedule C. If you have already filed your 2019 taxes, or prepared a 2019 return, this will be reported on line 31 of the Schedule C. If you have not filed your 2019 taxes, you will still need to fill out a Schedule C in order to qualify for the PPP.
Proof of income
The lender will want to see all documents related to any wage, commission, income, or net earnings from self-employment that you have received. This means that you’ll need to collect any earnings reports, pay stubs, or invoices you have.
Sole proprietorships will need to submit a Schedule C from their 2019 tax return filed (or to be filed) showing income and expenses from the sole proprietorship.
Independent contractors will need to submit schedules from their 2019 tax return filed (or to be filed) as well as Form 1099-MISC from 2019.
All self-employed individuals will need to submit 2019 payroll tax filings reported to the Internal Revenue Service.
Rent, mortgage, and utilities expense
The Paycheck Protection Program funding can cover your office lease, rent, or mortgage interest, provided that you had it before February 15 2020. If you have a home office, you can claim a portion of the expenses (the percentage of your home that’s used as a home office).
Again, collect any paid invoices, statements, lease agreements, or cancelled checks that will help prove you had these expenses.
However, if you want to have your loan forgiven, you must spend 75% of the loan funds on payroll costs (and the remaining 25% on rent, mortgage interest, and utilities).
If you’re a sole proprietor, 75% of the loan acts as a replacement for lost profit and does not need to be spent in a specific way. The remaining 25% must be spent on mortgage interest, rent and lease payments, and utilities in order to be forgiven.
Looking for business funding today?
PPP applications are closed. For other financing needs, apply for business funding with G-Force Funding. This is not a PPP application.
Financial records you’ll need
You’ll need to provide payroll/bookkeeping records to prove your payroll expenses.
That could include:
- Payroll processor records
- Payroll tax filings
- Form 1099-MISC records
- Schedule C for a sole proprietorship
- If you don’t have access to those kinds of documents, you can also provide bank records.
If you own more than one business
We are also hearing reports that entrepreneurs who own more than one business are having difficulty getting relief funding when their businesses don’t have cleanly separated finances. If you own more than one business, it’s important to get separate bookkeeping done for each business. This will become doubly important when it comes time to prove your expenses for loan forgiveness.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
PPP Loan Update – April 22
Archived 2020 article: The Paycheck Protection Program ended on May 31, 2021 and is closed to new applications. The original discussion below reflects early program rules and is not current application, forgiveness or tax guidance. Visit the SBA’s official COVID-era program resources for information about existing loans.
The Paycheck Protection Program (PPP) ran out of money last week. Despite its bumpy start, the program had approved more than 1.5 million applications from distressed small businesses in less than two weeks. As a result of the funding shortfall, the Small Business Administration (SBA) ceased taking applications from lending institutions.
After negotiating all weekend, the White House and Democrats are reporting that they are near a deal. Dubbed Stimulus 3.5, the new round of funding includes another $300 billion for the PPP, $50 billion for disaster relief loans (Economic Injury Disaster Loans), $75 billion for hospitals and $25 billion for testing. It’s being predicted that the new bill will be approved as early as today. Given the dire straits many of the nation’s 30 million small business find themselves in, hopefully businesses will be approved shortly afterward. For the moment, some banks will continue to accept applications for when the pipeline opens again. Others may tell small business owners just to have their applications ready.
PPP loans are a much needed lifeline. They can be for 2.5 times payroll costs, up to $10 million, and feature a streamlined application process and fewer conditions. Most importantly, PPP loans can be forgiven, fully or in part, depending on if borrowers maintain head counts and payrolls at pre-pandemic levels and use their loan for authorized expenses.
If you were going to apply for a PPP loan, which the SBA classifies as a 7( a) loan, you should still get your paperwork ready. Read on to understand what is required, how much you can borrow, how forgiveness works and other key specifics. You should also research other business relief options.
Do You Qualify for a PPP Loan?
Almost any small business with 500 or fewer employees may be eligible. This includes small businesses, corporations, LLCs, private nonprofits, faith-based organizations, tribal groups and veteran groups. Self-employed individuals who file an IRS Schedule C with their Form 1040, such as independent contractors and sole proprietors, are also eligible. (Partners who report self-employment income, however, are not eligible as self-employed individuals.).
Restaurants and hospitality businesses may qualify if they have 500 or fewer employees per location. Details on the size standards and exceptions are on the SBA website.
Ineligible enterprises include those engaged in illegal activities, owners more than 60 days delinquent on child support obligations, farms and ranches, sex businesses, lobbyists and gambling establishments.
Terms of a PPP Loan
The government’s aims to aid businesses have resulted in reasonable terms for PPP loans. Borrowers can receive two and a half times their average monthly payroll costs (excluding compensation in excess of $100,000 per employee) incurred 12 months before the date the loan is made (some lenders are just using 2019 numbers). For example, if your monthly average payroll (excluding compensation in excess of $100,000 salaries) in the last 12 months is $10,000, you may borrow up to $25,000. Furthermore, you can include as payroll costs: payment for vacation, parental, family, medical and sick leave (that is not covered by another emergency loan/grant); payment for dismissal or separation; payment for group health care coverage, including insurance premiums; payment for retirement benefits and payment of state and local taxes assessed on employees’ compensation.
Also, you can add to your total loan amount the outstanding amount of any Economic Injury Disaster Loan (EIDL) made between January 31, 2020 and April 3, 2020, less any “advance” that is forgivable under an EIDL COVID-19 loan.
With most Americans under some form of lockdown and businesses across the country closed, PPP loans are a necessary lifeline. They can be for 2.5 times payroll costs, up to $10 million, and feature a streamlined application process and fewer requirements. Most significantly, PPP loans can be forgiven, fully or in part, depending on if borrowers maintain head counts and payrolls at pre-pandemic levels and use their loan for permitted expenses.
If you were planning on apply for a PPP loan, which the SBA categorizes as a 7( a) loan, you should still get your paperwork prepared. Read on to understand what is required, how much you can borrow (use our PPP calculator, below), how forgiveness works and other key details. You should also research other business relief options. If you’re feeling overwhelmed, you can contact a representative from G-Force Funding for assistance by phone (305) 563-4361 or email: info@gforcefunding.com
PPP Loan Forgiveness
Small businesses will have their loans forgiven if they use the money for designated expenses. Participants are eligible for loan forgiveness for the amounts spent on authorized expenses over the eight weeks after the loan is disbursed.
The total payments for payroll over the eight weeks after the loan is disbursed may be forgiven. Mortgage interest, rent and utilities are also forgivable, up to 25% of the PPP loan.
To get the entire amount of the loan forgiven (assuming that at least 75% is spent on payroll and the rest on permitted expenses), you must meet two criteria. First, the full-time employee headcount can not decline from average monthly levels during 2019 or during the past 12 months. If your business started in the H2 of 2019, you can use average headcounts from January 1, 2020 to February 29, 2020. If you have a seasonal business, you can base your monthly averages on numbers from February 15, 2019, or March 1, 2019 to June 30, 2019.
Second, for loans to become full grants, employers can not cut salaries or wages. If they do, the forgiven amount will be reduced. Employers who already let workers go have until June 30 to restaff. The SBA has yet to issue guidance on how a smaller staff or payroll will reduce the amount eligible for forgiveness.
Another provision of the program allows borrowers who already have disaster assistance loans to defer payments through Dec. 31. This is an automatic deferment. Borrowers don’t have to do anything to qualify for it.
The SBA has a summary of loan terms here: https://home.treasury.gov/system/files/136/PPP–Fact-Sheet.pdf
How to apply for a PPP loan
Banks, primarily community banks, began accepting PPP loan applications from small businesses and sole proprietorships on April 3. Independent contractors and self-employed individuals, including freelancers, could apply starting April 10. The program ends June 30, though borrowers are encouraged to apply as soon as possible. Note that many lenders are limiting eligibility to those businesses with whom they have a pre-existing relationship, such as previous loans or a business checking account.
PPP applications are closed. For other financing needs, apply for business funding with G-Force Funding. This is not a PPP application.
Historical document list from April 2020:
- Completed SBA Paycheck Protection Program Application Form
- 2018 (or 2019) personal and biz tax return
- Last 6 months bank statements and MTD
- All owners’ Driver’s Licenses (front and back)
- IRS Form 940 and 941 (as of 12/31/19 and 3/31/20, respectively)
- Payroll Report for February 15, 2020 (or closest date).
- Annual Payroll Report for 2019 (calendar year through December 31, 2019)
- If an SBA EIDL loan was made between 1/31/2020 and 4/3/2020, a copy of the note
Here is a side by side comparison of the PPP loan & EIDL loan:
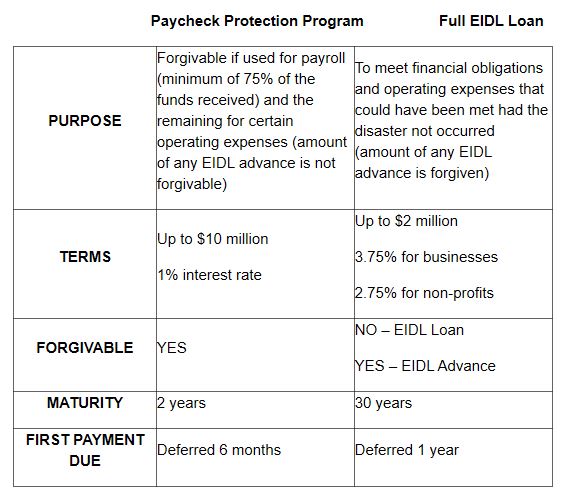
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Everything You Need To Know About The CARES Act
Historical archive: This article reflects pandemic-era information at its original publication date. Program rules and deadlines changed afterward. PPP ended on May 31, 2021 and is closed to new loan applications. The material below is not current application, forgiveness or tax guidance.
Consult the SBA’s official COVID-era program resources and your lender for existing-loan assistance. For new financing needs, compare our business credit guide and startup funding options.
Original historical article
The Senate has actually passed a roughly $2 trillion coronavirus response bill intended to speed relief across the American economy. This is the 3rd aid bundle from Congress and is suggested to keep organisations and people afloat during an unprecedented freeze on the majority of American life.
Senate Majority Leader Mitch McConnell, explained the legislation, known as the CARES Act, as essential emergency situation relief and pledged to put partisanship aside to get it done.
“No economic policy can fully end the difficulty so long as the general public health needs that we put so much of our commerce on ice,” McConnell said in a speech on the Senate floor on Wednesday. “This isn’t even a stimulus package. It is emergency relief. Emergency relief. That’s what this is.”
There are 7 primary groups that would see the widest-reaching effects: individuales, small businesses, big corporations, health centers and public health, federal safeguard, state and local governments, and education.
Here’s what each group can anticipate if this bill ends up being law.
INDIVIDUALS
The bill consists of a number of aspects targeted at helping keep individuals engaged in the economy. That implies direct cash for numerous, plus broadened welfare and new guidelines for things like submitting your taxes and making retirement contributions.
Money Payments: Estimated to amount to $300 billion. People making less than $75,000 can expect a one-time money payment of $1,200. Married couples would each get a check and families would get $500 per child. That implies a household of 4 earning less than $150,000 can expect $3,400.
The checks start to phase down after that and disappear totally for individuals making more than $99,000 and couples making more than $198,000.
The cash payments are based upon either your 2018 or 2019 tax filings. People who receive Social Security benefits however don’t file tax return are still qualified, too. They don’t need to submit taxes; their checks will be based upon info offered by the Social Security Administration.
Additional Unemployment Payments: The $260 billion estimated cost undergoes change based on the variety of individuals declaring unemployment.
The bill makes major changes to unemployment support, increasing the benefits and widening who is qualified. States will still continue to pay joblessness to people who certify. That amount varies state by state, as does the amount of time individuals are allowed to claim it.
This expense adds $600 weekly from the federal government on top of whatever base quantity a worker gets from the state. That improved payment will last for 4 months.
For example, if an out-of-work person is getting the national average of about $340 each week, under the brand-new federal program their net earnings will be $940.
The legislation also adds 13 weeks of unemployment insurance. People nearing the maximum number of weeks allowed by their state would get an extension. New filers would likewise be enabled to gather the advantages for the longer period.
Gig Workers and Freelancers: Typically, self-employed individuals, freelancers and specialists can’t make an application for unemployment. This bill produces a new, short-term Pandemic Unemployment Assistance program through completion of this year to help individuals who lose work as a direct outcome of the public health emergency situation.
Income tax return: Some individuals have actually not submitted their 2019 tax returns, however that’s OK. The filing deadline has been reached July 15. The IRS likewise says that people who have actually submitted or plan to can still anticipate to get a refund if they are owed one.
Trainee Loans: Employers can provide up to $5,250 in tax-free student loan payment benefits. That implies an employer might contribute to loan payments and employees wouldn’t have to consist of that cash as earnings.
Insurance coverage Coverage: The bill requires all personal insurance coverage plans to cover COVID-19 treatments and vaccine and makes all coronavirus tests free.
SMALL BUSINESSES
The highlights for small companies are emergency grants and a forgivable loan program for companies with 500 or fewer workers. There are likewise modifications to guidelines for expenditures and reductions meant to make it easier for companies to keep workers on the payroll and stay open in the near-term.
Emergency Grants: The expense provides $10 billion for grants of as much as $10,000 to supply emergency funds for small companies to cover instant operating expense.
You can apply for an immediate $10,000 grant with the SBA here:
COVID-19 ECONOMIC INJURY DISASTER LOAN APPLICATION
Paycheck Protection Program Loans – Forgivable Loans: There is $350 billion designated for the Small Business Administration to provide PPP loans of up to $10 million per organisation. Any portion of that loan utilized to keep payroll, keep workers on the books or pay for rent, home mortgage and existing financial obligation could be forgiven, provided workers stay utilized through end of June.
You can apply for Paycheck Protection Program (PPP) loans with your bank or immediately with G-Force Funding here:
PPP (PAYCHECK PROTECTION PROGRAM) LOAN APPLICATION
Relief For Existing Loans: There is $17 billion to cover 6 months of payments for small businesses currently utilizing SBA loans.
BIG BUSINESSES
The bill sets aside approximately $500 billion in loans and other cash for large corporations. These companies will have to pay the government back and will be subject to public disclosures and other requirements.
Airlines: About $58 billion is allocated to assist airline companies stay open. One part of that cash is set aside to assist cover staff member salaries, wages and advantages divided up as approximately $25 billion for traveler air providers, up to $4 billion for freight air carriers, and as much as $3 billion for airline company professionals.
Stock Buyback Ban: Any company getting a loan under the program is disallowed from making stock buybacks for the term of the loan plus one year.
Reporting Requirements: All loans, their terms and any financial investments or other help supplied by the federal government must be publicly divulged.
Oversight: The bill creates a special inspector general to supervise pandemic healing. That individual, along with a special committee, would supply oversight of all loans and other uses of taxpayer dollars.
No Benefit For Politicians: The president, vice president, members of the Cabinet and members of Congress are disallowed from benefiting from the money took for corporations. That likewise reaches the “spouse, child, son-in-law or daughter-in-law.”
All Businesses: The bill develops a completely refundable tax credit for organisations of all size that are closed or distressed to help them keep workers on the payroll. The goal is to get those workers worked with back or put on paid furlough to make certain they have tasks to go back to. The credit covers to 50 percent of payroll on the very first $10,000 of compensation, including health benefits, for each employee.
For Employers with more than 100 full-time workers, the credit is for wages paid to workers when they are not offering services because of the coronavirus. Eligible companies with 100 or fewer full-time staff members might utilize the deduction even if they aren’t closed.
PUBLIC HEALTH
Lawmakers want to supplement community and personal health systems to help fulfill the increase of brand-new patients.
Hospitals: There is $100 billion for health centers responding to the coronavirus.
Community Health Centers: The expense supplies $1.32 billion in immediate extra financing for community centers that provide health care services for approximately 28 million individuals.
Drug Access: There is $11 billion for diagnostics, treatments and vaccines. The bill likewise includes $80 million for the Food and Drug Administration to prioritize and accelerate approval of brand-new drugs.
Centers For Disease Control and Prevention: CDC programs and action efforts are getting $4.3 billion.
Veterans’ Health Care: There is $20 billion set aside for veterans.
Telehealth: The bill reauthorizes a vital telehealth program to extend the reach of virtual doctors appointments.
Medication and Supplies: The bill provides $16 billion to the Strategic National Stockpile to increase accessibility of equipment, consisting of ventilators and masks. It likewise increases hiring for essential healthcare tasks during the public health crisis and speeds the advancement of a vaccine, treatments and faster diagnostic.
SAFETY NET
This is the 2nd wave of financing for significant food security programs.
Child Nutrition: There is $8.8 billion to provide schools more versatility to supply meals for students.
Food Stamps: $15.5 billion is going to the Supplemental Nutrition Assistance Program, also called SNAP. The money will help cover the expected expense of brand-new applications to the program as an outcome of the coronavirus.
American Indian Reservations, Puerto Rico, Northern Mariana Islands and American Samoa all get extra funds and access to federal nutrition programs.
Food Banks: There is $450 million more for food banks and other community food circulation programs.
MENTION AND LOCAL GOVERNMENTS
The legislation designates $339.8 billion for programs that will go to state and city governments. It is divided up to put $274 billion towards specific COVID-19 reaction efforts, including $150 billion in direct aid for those state and city governments running out of money due to the fact that of a high number of cases.
It likewise consists of $5 billion for Community Development Block Grants, $13 billion for K-12 schools, $14 billion for greater education and $5.3 billion for programs for kids and households, consisting of instant assistance to kid care.
EDUCATION
The bill consists of relief for college students and graduates with impressive federal student debt.
Short-term Student Loan Relief: All loan and interest payments would be deferred through Sept. 30 without penalty to the customer for all federally owned trainee loans.
Work-Study Funds: It permits schools to turn unused work-study funds into supplemental grants and continue paying work-study salaries while schools are suspended.
Trainees Who Are Forced To Drop Out: Students who leave of school as an outcome of the coronavirus would not have that time far from school deducted from their lifetime limits on subsidized loan and Pell Grant eligibility. Those students would also not be asked to repay any grants or other aid they’ve already gotten.
OTHER PROGRAMS
There is a very long list of other locations getting financing consisting of arts programs, universities and other institutions.
Please email any questions you have to info@gforcefunding.com
Thank you & please stay safe!
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
Secured vs. Unsecured Business Loans: What to Compare
Updated September 30, 2026.
The main difference between secured and unsecured business loans is collateral. A secured loan is backed by pledged assets; an unsecured loan is not backed by specific collateral. Neither label, by itself, tells you the total cost or whether an owner must sign a personal guarantee.
Compare the obligations, not just the label
| Question | Secured loan | Unsecured loan |
|---|---|---|
| Is collateral pledged? | Yes. The agreement identifies the covered assets. | No specific collateral, but confirm the actual agreement and any lien provisions. |
| Can a personal guarantee apply? | Yes, in addition to collateral. | Yes. Unsecured does not mean no personal liability. |
| Is approval assured? | No. Collateral is only one part of underwriting. | No. Repayment capacity and other eligibility requirements still matter. |
| Which costs less? | Compare actual rates, fees, payment schedules and total repayment. The label is not enough. | |
When a secured loan may fit
A business purchasing equipment may consider a loan secured by that equipment. A company with eligible receivables or inventory may consider an asset-based facility. The collateral can support financing, but valuation, existing liens and the lender’s advance limits affect availability.
Consider the operational consequences if an essential asset were lost. Read our secured business loan guide for collateral types and application preparation.
When an unsecured loan may fit
A business may prefer to avoid pledging a specific asset, or may have few eligible assets. That does not mean every unsecured product will fit its budget or qualifications. Ask whether the provider requires a guarantee, credit inquiry or any security interest despite marketing language such as “no collateral.”
There is no universal revenue threshold, minimum time in business or credit score for all unsecured business loans. Obtain requirements for the actual product before applying.
Compare two written offers
- Net proceeds: How much reaches your business after fees?
- Cost: What are the interest rate, APR where supplied, total repayment and all charges?
- Payment pressure: Are payments daily, weekly or monthly? Can your business pay during a slower sales period?
- Asset and owner exposure: Which assets and guarantees support the debt, and what happens after default?
- Flexibility: Review early repayment, renewals, restrictions on additional borrowing and lien-release requirements.
Questions about personal guarantees
A personal guarantee is an owner’s or other guarantor’s promise to pay under its terms. It differs from granting a lien on a particular asset. Ask whether the guarantee is limited or unlimited and when it can be released. Have a qualified attorney review unclear provisions before you commit.
Choose payments your business can support
Start with a repayment forecast, then compare available offers. If revolving access may better match your needs, review our business line of credit guide.
Discuss financing with G-Force Funding or call (305) 563-4361. Approval and terms depend on the provider and application.
Content & Creative Writer | Blogger | Small Business Funding Advocate | Effective Communications | Entrepreneur |Traveler
